ABE MAGAZINE | ABE ORIGINAL
November 14, 2026
By ABE Editorial Desk
The modern economy depends on infrastructure most people rarely think about until something goes wrong. Electricity travels through networks that power homes and factories. Airports connect businesses to international markets, water systems sustain entire cities, and data centres support the digital services increasingly embedded in everyday life. These assets appear permanent, almost inseparable from the countries they serve. Yet the ownership behind them is undergoing a significant transformation.
Across the world, investment managers, pension funds and private equity firms are acquiring stakes in businesses that operate essential infrastructure. Governments facing enormous investment requirements are increasingly willing to work with private capital, while investors see opportunities in assets with long operating lives and persistent demand. The result is a changing relationship between public services, financial markets and economic power. The question is not simply who owns these assets, but how ownership influences investment, accountability and the public interest.
The Trillion-Dollar Competition for Infrastructure
The financial scale of infrastructure investment helps explain why private capital has become so influential. McKinsey estimates that approximately $106 trillion will be needed globally through 2040 to develop and maintain infrastructure, including transport systems, electricity networks, digital facilities and other essential assets. In 2025, private infrastructure fundraising reached nearly $200 billion, reflecting growing institutional interest in the sector.
These figures do not mean that governments are selling all their infrastructure. Much of the investment involves developing new facilities, expanding existing networks or financing businesses that have long operated privately. Nevertheless, the growing volume of institutional capital is changing who participates in decisions about infrastructure development and how those decisions are financed.
The attraction is understandable. Infrastructure often supports services that remain necessary regardless of economic conditions. Electricity must be delivered, water must be treated and goods must move through transport networks. Such demand can create relatively predictable revenue, although returns depend heavily on regulation, operating performance and the amount investors pay to acquire assets.
For financial institutions managing retirement savings and other long-term capital, these characteristics can be appealing. Infrastructure offers the possibility of combining durable assets with investment horizons extending over decades. Yet the same qualities that attract investors also make the assets particularly important to the public.
BlackRock and the Rise of Infrastructure Giants
One of the clearest examples of the industry’s transformation came in October 2024, when BlackRock completed its acquisition of Global Infrastructure Partners. The combined platform began operating with approximately $170 billion in assets under management and more than 300 active investments across over 100 countries.
The transaction demonstrated how infrastructure has moved closer to the centre of global investment management. Rather than treating airports, energy networks and digital facilities as specialised investments, major financial institutions increasingly view them as a significant component of diversified portfolios.
BlackRock’s expansion also reflects the growing importance of scale. Large investment platforms can assemble capital from pension funds, insurers and other institutions, allowing them to participate in projects that would be difficult for smaller investors to finance independently. Their experience can support operational improvements, but size also raises questions about the concentration of financial influence.
A company managing infrastructure investments does not necessarily own every underlying asset outright. Funds often hold minority interests, operate through partnerships or invest alongside governments and other shareholders. Nevertheless, the institutions managing these funds can exercise meaningful influence through board representation, financing arrangements and investment decisions.
The distinction between ownership and control is therefore essential. Financial influence can extend beyond the percentage of shares held, particularly when an investor possesses expertise, capital and contractual rights that other shareholders depend upon.
Manchester Airport: When Public and Private Ownership Meet
Britain’s Manchester Airports Group offers a practical example of how infrastructure ownership can combine public institutions with private investment. The group operates Manchester, London Stansted and East Midlands airports, serving important regional and international transport markets.
According to the group’s 2025 financing prospectus, the City of Manchester Council owns 35.5%, other Greater Manchester councils collectively hold 29%, and the IFM Global Infrastructure Fund holds 35.5%. Voting control is shared equally between Manchester City Council and IFM.
This structure challenges the assumption that infrastructure must be either entirely public or entirely private. Local authorities retain a majority of the economic ownership, while an institutional investor participates in governance and long-term development. IFM, which invests on behalf of institutional clients, first acquired its interest in 2013.
The arrangement creates potential benefits. Private investment expertise can support expansion, commercial management and long-term planning, while public shareholders retain a direct interest in employment, regional development and airport connectivity.
However, mixed ownership does not automatically resolve disagreements. Decisions about passenger charges, capital expenditure, environmental commitments and commercial returns can involve competing priorities. The effectiveness of such partnerships depends on clear governance and a shared understanding of what the infrastructure is expected to deliver.
Manchester demonstrates that the central question is not always whether private capital should participate. It is whether the ownership structure preserves accountability while providing the resources necessary for development.
Thames Water: The Risks Behind Financial Engineering
The experience of Thames Water reveals the more difficult side of infrastructure investment. In 2006, a consortium led by Macquarie-managed funds acquired the British water utility from German energy company RWE. Macquarie-managed funds held approximately 48% of the business, with other investors participating alongside them.
During the ownership period, the company undertook substantial infrastructure investment. Macquarie reports that Thames Water invested an average of more than £1 billion annually between 2006 and 2017 to maintain and expand its network. The company’s regulated asset base increased from approximately £6 billion to £13 billion.
Yet its debt also increased, from approximately £6 billion to £11 billion over the same period. Macquarie maintains that the borrowing supported investment and remained proportionate to the regulated asset base. The company also says Thames Water maintained an investment-grade credit rating during its ownership.
The figures nevertheless illustrate a fundamental challenge in infrastructure finance. Essential services require substantial investment, but borrowing introduces obligations that must eventually be supported by operating cash flow, customer charges or additional financing.
Thames Water subsequently experienced severe financial and operational difficulties, drawing scrutiny from regulators, policymakers and the public. Its problems cannot be attributed solely to one former shareholder or one financing decision. They involve a longer history of investment requirements, environmental performance, regulatory decisions and financial pressures.
The broader lesson is that infrastructure investment must be evaluated across decades. An ownership model can deliver improvements during one period while leaving future operators exposed to difficult financial conditions. Public accountability therefore requires attention not only to immediate investment commitments, but also to debt, asset condition and long-term resilience.
The New Infrastructure Is Digital
The definition of essential infrastructure is expanding. Data centres, fibre networks and computing facilities have become increasingly important to businesses, governments and households. Their importance is growing as digital services and artificial intelligence increase demand for computing capacity.
McKinsey estimates that nearly $7 trillion in data centre investment may be required through 2030. S&P Global Market Intelligence reported that global private equity and venture capital investment in utilities reached approximately $69.5 billion in 2025, with rising electricity demand from data centres helping attract capital into the sector.
These developments are connecting previously separate industries. A data centre requires reliable electricity, communications networks, cooling systems and physical security. Investors financing computing facilities may also seek exposure to power generation, energy storage and transmission infrastructure.
This creates opportunities for coordinated investment, but it also introduces new dependencies. If a small number of companies control important facilities or supply arrangements, their commercial decisions may influence the cost and availability of digital services.
Governments are consequently facing questions about energy allocation, competition, cybersecurity and national resilience. Infrastructure ownership is no longer limited to physical transport and utilities. It increasingly shapes access to the digital systems through which modern economies operate.
Why Governments Are Turning to Private Capital
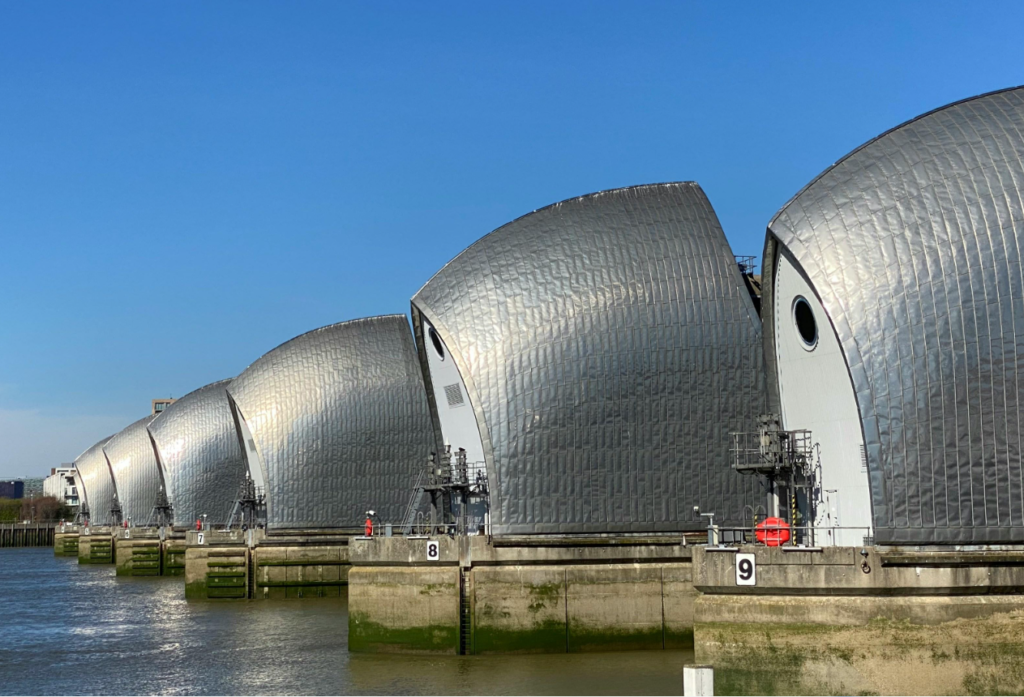
Governments face difficult choices when financing infrastructure. Ageing facilities require maintenance, populations demand better services, and new technologies create investment needs that compete with healthcare, education and other public priorities.
Private capital can help address these pressures by financing projects, sharing certain risks and providing operational expertise. It can also accelerate development when public budgets or administrative processes limit the pace of investment.
However, private financing is not free money. Investors expect returns, and those returns must ultimately come from commercial revenue, regulated charges, government payments or asset appreciation. Transferring financing responsibility does not necessarily eliminate the economic cost borne by taxpayers and consumers.
The appropriate ownership model therefore depends on the asset, the regulatory environment and the allocation of risk. Competitive infrastructure businesses may respond effectively to market incentives, while natural monopolies such as water distribution networks require particularly strong oversight.
Governments must also consider what happens when private investors seek to sell, refinance or restructure their holdings. Infrastructure may remain physically located within a country, but its ownership can change through financial transactions involving institutions headquartered elsewhere.
The challenge is designing agreements that attract investment without weakening the public’s ability to hold operators accountable.
Who Ultimately Holds the Power?
Infrastructure ownership is often less straightforward than the name displayed on a facility. An airport may be operated by one company, owned through a holding structure and financed by several investment funds. Those funds may manage money for pension schemes, insurance companies and sovereign wealth institutions.
This creates a chain of financial relationships connecting essential services to investors around the world. In some cases, the ultimate beneficiaries include ordinary workers whose retirement savings are invested through pension funds. Private ownership is therefore not always a simple conflict between wealthy investors and the public.
Nevertheless, the interests of pension beneficiaries, infrastructure customers and local communities are not identical. A pension fund seeks attractive risk-adjusted returns, while households want affordable services and governments want reliable infrastructure. Those objectives can reinforce one another, but they can also conflict.
Transparency becomes especially important when ownership structures are complex. Citizens need to know who makes major decisions, how investment obligations are enforced and which institutions bear responsibility when services deteriorate.
The future of infrastructure may depend less on choosing between public and private ownership than on establishing governance systems capable of managing both.
THE ABE TAKE
The growing influence of private capital over essential infrastructure reflects a genuine economic challenge. Modern societies require enormous investment, and governments cannot always provide the financing, expertise or operational capacity necessary to meet every demand. Institutional investors can play a constructive role in developing the systems that support economic growth.
But infrastructure is fundamentally different from an ordinary commercial investment. People cannot simply stop using water networks, electricity systems or major transport connections when ownership decisions produce poor outcomes. These assets carry responsibilities that extend beyond financial performance.
The experiences of Manchester Airports Group and Thames Water demonstrate why ownership structure alone cannot determine success. Partnerships can combine public accountability with private expertise, while poorly managed financial risks can undermine the stability of essential services. Outcomes depend on regulation, investment discipline, governance and the distribution of responsibility.
The emergence of digital infrastructure makes these questions more urgent. Control over data centres, communications networks and energy supply increasingly influences economic competitiveness and technological development.
The world’s essential infrastructure does not belong to one class of investor, nor is it uniformly moving into private hands. Yet financial institutions are becoming increasingly important participants in how these assets are owned, financed and operated.
The decisive question is not whether private capital should help build the future. It is whether the institutions controlling essential infrastructure can be held accountable to the societies that depend upon it.
ABE MAGAZINE
Understand More. Think Bigger.