By ABE Magazine | Business Insights | November 1, 2026
Banks are among the most powerful businesses in the world because they occupy a central position in the movement of money. They accept deposits, provide credit, facilitate payments and connect households, businesses and governments to the financial system.
Unlike ordinary companies, banks do not simply sell products or services. They help determine how financial resources move through an economy.
A bank’s decision to approve a mortgage can influence a family’s ability to purchase a home. Its decision to finance a company can support expansion, employment and investment. Its lending policies can also affect entire industries.
This economic influence is supported by a business model that can generate substantial revenue from activities many customers barely notice.
Understanding the banking business means looking beyond branches, debit cards and mobile applications to examine how banks make money, manage risk and maintain their position in the economy.
How Banks Actually Make Money
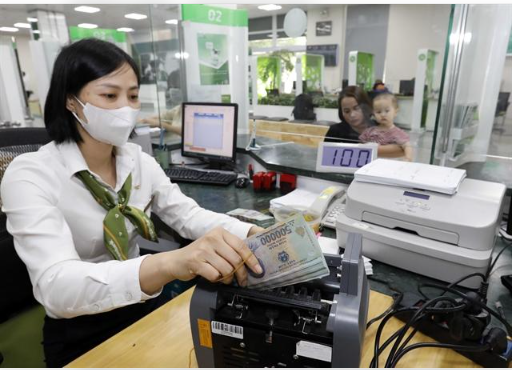
One of the most important sources of banking revenue is the difference between interest earned on assets and interest paid on funding.
Banks accept deposits from customers and use deposits alongside other funding sources to support lending and investment activities.
When a bank issues a mortgage or business loan, it generally charges interest. It may pay depositors a lower interest rate on eligible savings products.
The difference contributes to net interest income.
However, banks cannot simply lend out all deposited money without restrictions. They must manage liquidity, maintain regulatory capital and meet obligations to depositors and other creditors.
Banks also generate substantial non-interest income.
This includes payment-related fees, wealth management, investment banking, trading services, insurance-related activities and other financial products, depending on the institution.
A diversified bank may therefore earn revenue from both traditional lending and a broad range of financial services.
The Economic Power of Credit
Credit is one of the main reasons banks have such significant influence.
Most businesses cannot finance every investment entirely from existing cash.
They may need loans to purchase equipment, acquire property, manage inventory or expand into new markets.
Households similarly rely on mortgages and other credit products for major purchases.
Banks assess borrowers and decide whether financing is available, at what price and under what conditions.
These decisions influence investment and consumption.
When banks become more cautious, credit availability can decline. Businesses may postpone expansion, and households may reduce borrowing.
When lending conditions become more supportive, investment and spending may increase.
Banks do not control economic growth by themselves. Interest rates, government policy, capital markets and consumer confidence also matter.
Nevertheless, their position as credit providers gives them an important role in shaping economic activity.
Why Large Banks Have Competitive Advantages
Major banks often benefit from established customer relationships, recognizable brands and extensive financial infrastructure.
They can serve individuals, small businesses, large corporations and institutional clients through multiple divisions.
A customer may use the same bank for a chequing account, mortgage, investment products and business financing.
This creates opportunities for long-term relationships and additional services.
Large banks may also spread technology, compliance and operating costs across extensive customer bases.
Their size can support investments in cybersecurity, digital banking platforms and sophisticated risk management systems.
However, size does not eliminate financial risk.
Large institutions can experience substantial losses, liquidity pressure or operational failures.
Regulatory supervision is particularly important because problems at major banks can have consequences beyond their shareholders.
The Power of Payment Networks
Banks also play a central role in the payment system.
Businesses and consumers depend on financial institutions to transfer money, process transactions and settle financial obligations.
When a customer pays with a debit card or sends a bank transfer, several institutions and technical systems may participate in the transaction.
The bank’s role depends on the payment method and the financial infrastructure involved.
Not all payment systems are owned or controlled by banks. Card networks, payment processors, fintech companies and central-bank infrastructure also play important roles.
However, banks remain critical providers of accounts, regulated financial services and access to settlement arrangements.
Their position in payments strengthens customer relationships and creates opportunities for service revenue.
It also makes reliability essential.
A major banking outage can interrupt payroll, retail transactions and ordinary household spending.
Why Banking Is Heavily Regulated
Banking creates risks that extend beyond an individual company.
Banks fund long-term assets, such as mortgages, partly through liabilities that customers may be able to withdraw on demand.
This difference between asset and liability maturities requires careful liquidity management.
Banks also face credit risk when borrowers fail to repay loans.
Other risks include interest-rate changes, fraud, cyberattacks and market volatility.
Because banks are interconnected with the wider economy, governments establish regulatory and supervisory frameworks intended to reduce the likelihood and consequences of financial instability.
In Canada, federally regulated banks are supervised by the Office of the Superintendent of Financial Institutions.
The Bank of Canada also plays an important role in monetary policy, financial stability and payment-system oversight.
These institutions perform different functions, but together they contribute to the broader framework supporting Canada’s financial system.
Canada’s Banking Industry as a Case Study
Canada’s banking sector illustrates how a relatively small group of large institutions can occupy important positions across the economy.
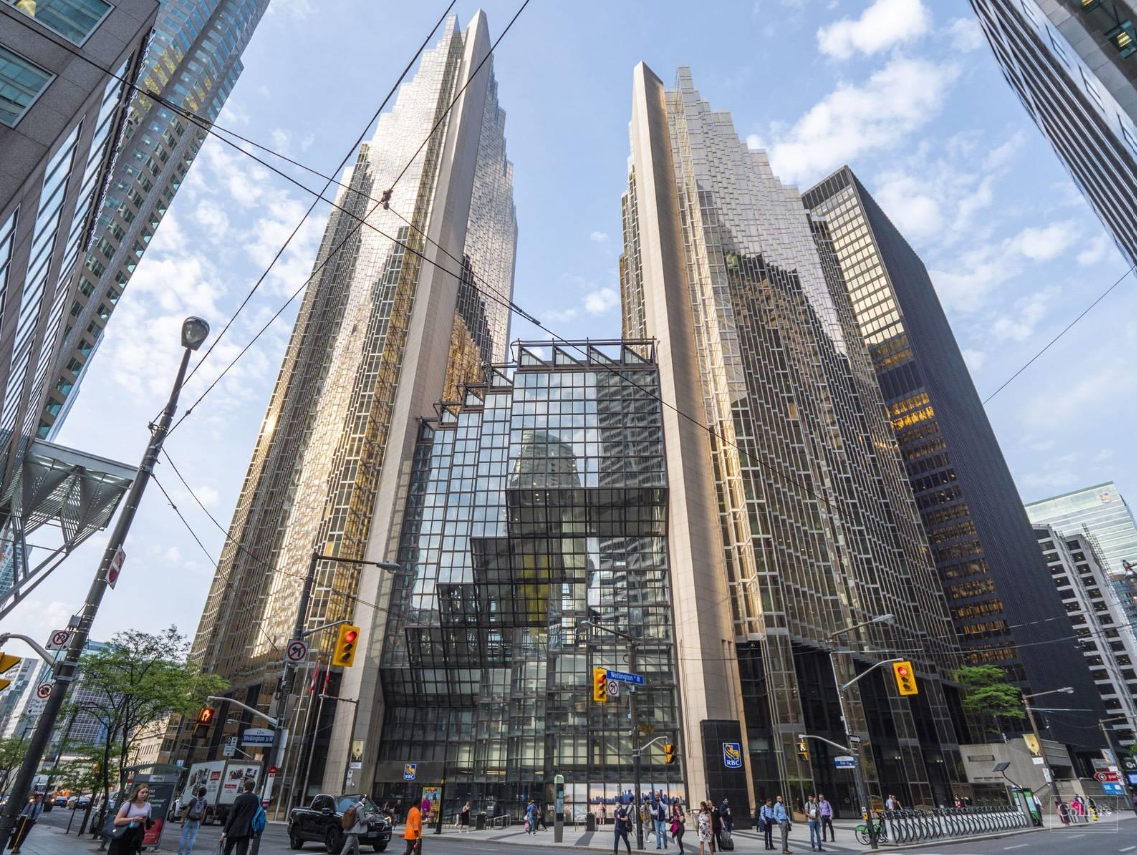
The country’s six major banks are Royal Bank of Canada, Toronto-Dominion Bank, Bank of Nova Scotia, Bank of Montreal, Canadian Imperial Bank of Commerce and National Bank of Canada.
Their operations extend across personal banking, commercial lending, wealth management, capital markets and international financial services.
These institutions have substantial customer bases and established distribution networks.
However, they also face competition from smaller banks, credit unions and financial technology companies.
Digital-first providers have changed customer expectations by offering online account opening, simplified interfaces and alternative pricing models.
For traditional banks, competition increasingly involves customer experience and technology alongside financial strength.
How Fintech Is Challenging Traditional Banks
Financial technology companies have introduced new ways for consumers and businesses to access financial services.
Digital banking applications, online investment platforms and specialized payment services can provide convenient alternatives to traditional products.
Some fintech companies operate as regulated financial institutions, while others partner with banks or other licensed providers.
Their business models vary significantly.
For customers, digital competition may improve convenience, transparency and product choice.
For established banks, it creates pressure to modernize technology and reduce unnecessary complexity.
However, fintech companies face their own challenges.
Customer acquisition, cybersecurity, compliance and profitability can be expensive.
Traditional banks also retain advantages in funding, regulatory experience and established relationships.
The future of financial services is therefore unlikely to involve a simple replacement of banks by technology companies.
It is more likely to involve continuing competition and partnerships between different types of financial institutions.
The Risks Behind Banking Profits
Banking can be highly profitable, but it is not a risk-free business.
A bank may report substantial revenue while facing deteriorating credit quality or increasing funding costs.
Higher interest rates can support income on some assets while increasing borrowing costs for customers and creating pressure on loan repayments.
Economic downturns may lead to greater credit losses.
Banks must therefore evaluate profitability alongside capital strength, liquidity and asset quality.
Investors commonly examine measures such as return on equity, net interest margin, efficiency ratios and provisions for credit losses.
No single metric provides a complete picture.
A bank that increases short-term profits by taking excessive risk may undermine its long-term stability.
The strongest banking businesses must balance revenue generation with disciplined risk management.
The Future of Banking Power
Banking is becoming increasingly digital, but the industry’s fundamental role remains significant.
Households still need safe places to hold money, businesses still require financing and economies still depend on reliable payment systems.
Artificial intelligence may improve fraud detection, customer service and certain operational processes.
Digital infrastructure may reduce costs and expand access to financial services.
At the same time, banks will face growing expectations around cybersecurity, transparency and operational resilience.
The institutions that succeed will need more than large balance sheets.
They will need customer trust, sound risk management and the ability to adapt to technological change.
THE ABE TAKE
Banks occupy an unusually influential position because they combine commercial activities with functions that are essential to the wider economy.
Their profitability comes from lending, payments, investment services and other financial activities.
Their power comes from something broader: their role in allocating credit and maintaining access to financial infrastructure.
This influence also creates responsibilities.
Poor decisions at a major financial institution can affect borrowers, depositors, employees and other businesses.
For investors and business leaders, understanding banks requires looking beyond headline profits to examine the quality of their assets, funding structures and risk management.
The most powerful banks are not simply those that hold the most money. They are the institutions that can allocate capital effectively while maintaining the confidence of customers and the wider financial system.
ABE MAGAZINE
Understand More. Think Bigger.