ABE MAGAZINE | FINANCIAL MARKETS
October 16, 2026
Wall Street’s powerful stock-market rally is entering a more demanding phase as investors turn their attention to corporate earnings. After months of enthusiasm surrounding technology companies and strong business investment, rising borrowing costs, mixed banking results and questions about company valuations are testing confidence. The coming earnings reports could determine whether the market’s optimism is supported by financial performance or has moved ahead of economic reality.
A Rally That Now Needs Stronger Evidence
Wall Street is approaching a critical moment. U.S. stock markets remain close to record levels, but investors are becoming increasingly selective about the companies they are willing to support. Strong expectations for corporate profits are colliding with higher interest rates, expensive share valuations and uncertainty about the sustainability of recent market gains.
On October 15, the S&P 500 closed at 7,744.06, rising 0.3%, while the Dow Jones Industrial Average gained 1.1% and the Nasdaq Composite advanced just 0.1%. The modest recovery followed renewed volatility in technology shares, demonstrating how quickly sentiment can shift even when major indexes remain near their highs.
The immediate test is the third-quarter earnings season. Analysts expect profits among S&P 500 companies to increase by approximately 30.6% from a year earlier, an unusually strong forecast that leaves little room for disappointment.
For investors, the question is no longer simply whether companies are growing. It is whether their earnings can grow quickly enough to justify the prices already being paid for their shares.
Technology Companies Carry Much of the Market’s Expectations
A significant portion of Wall Street’s rally has been concentrated in large technology companies. Their rising market values have helped lift major stock indexes, while investment in computing infrastructure and advanced semiconductor manufacturing has supported expectations of future profitability.
However, concentration creates vulnerability. According to Reuters, analysts estimate that S&P 500 earnings growth would be approximately 5% without the contribution of the largest technology companies commonly grouped as the Magnificent Seven.
That difference reveals how heavily overall market performance depends on a relatively small number of businesses. Strong results from those companies can support investor confidence, but weaker earnings or disappointing forecasts could place pressure on the broader market.
The semiconductor industry offers an example of this tension. Taiwan Semiconductor Manufacturing Company reported a substantial increase in third-quarter profit, supported by strong demand for advanced chips. Yet positive earnings did not immediately reverse the wider decline in technology-related shares.
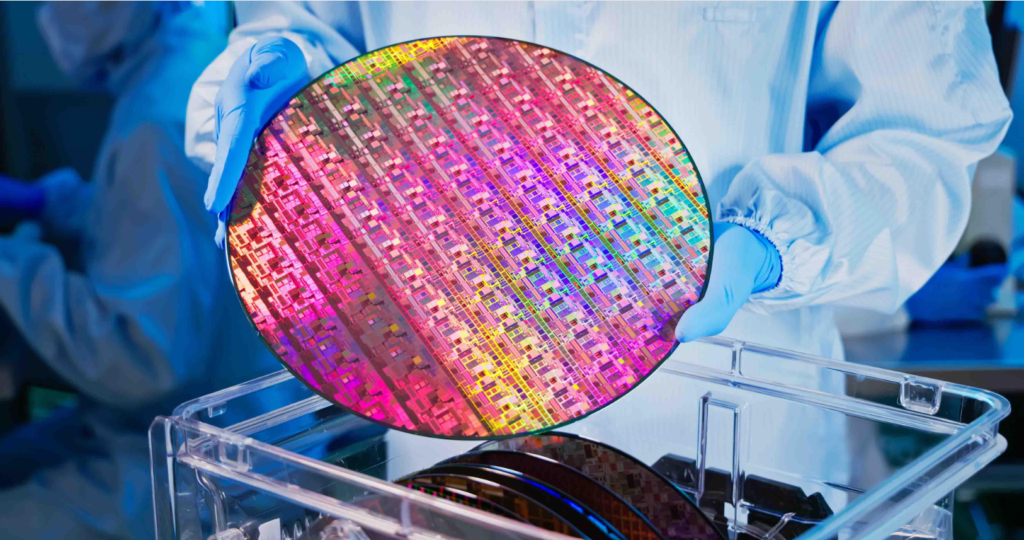
Investors are increasingly demanding evidence that large capital investments will produce sustainable financial returns rather than relying solely on expectations of future growth.
Bank Earnings Reveal a More Complicated Economy
The opening phase of earnings season has produced mixed signals from America’s largest banks. Their results suggest that consumer activity remains resilient, but the financial environment is becoming more challenging for businesses dependent on investment banking and corporate transactions.
JPMorgan Chase and Bank of America reported profits below market expectations, while other major banks delivered results that exceeded forecasts. Even positive earnings announcements received a restrained response from investors.
Goldman Sachs reported third-quarter net earnings of $5.29 billion on revenue of $18.68 billion, demonstrating that substantial profitability remains possible despite economic uncertainty.
However, the broader banking sector has experienced slower dealmaking activity. Higher bond yields, market volatility and geopolitical concerns have encouraged companies to delay mergers, acquisitions and public share offerings.
This matters because investment banking activity often reflects corporate confidence. When businesses postpone major transactions, it can indicate uncertainty about financing costs, valuations and future economic conditions.
At the same time, consumer lending and spending have remained relatively steady, suggesting that the economy is not experiencing uniform weakness.
Rising Interest Rates Change the Investment Calculation
Corporate earnings are only one factor determining stock prices. Interest rates also influence how investors value companies, particularly those whose expected profits lie several years in the future.
When borrowing costs rise, businesses may face greater expenses when financing expansion, refinancing debt or investing in new projects. Higher bond yields can also make fixed-income investments more attractive relative to equities.
Recent inflation figures have complicated the outlook. U.S. consumer prices increased 3.7% over the year to September, renewing concerns that the Federal Reserve may need to maintain restrictive monetary conditions or consider further tightening.
These pressures are especially important for companies investing heavily in infrastructure. Large spending commitments may be manageable when financing is inexpensive, but higher rates increase the returns required to justify those investments.
For investors, this changes the standard by which growth companies are assessed. Revenue expansion alone may no longer be sufficient if the costs of generating that growth are increasing.
The result is a market increasingly focused on cash flow, profitability and the financial sustainability of corporate investment.
The Next Earnings Reports Could Shape Market Confidence
Attention is now turning to another group of major corporate reports, including Meta Platforms, Tesla, IBM and several semiconductor companies.
Their results will provide investors with additional evidence about consumer demand, business spending, technology investment and corporate profitability.
The stakes are particularly high for companies undertaking substantial infrastructure projects. Investors want to understand not only how much businesses are spending, but when those investments will begin producing meaningful returns.
A strong earnings season could help support stock valuations despite higher interest rates. However, disappointing forecasts or signs of weakening demand could encourage investors to reduce their exposure to expensive shares.
Market leadership may also broaden if investors shift toward companies outside the largest technology groups. Such a change would not necessarily indicate the end of the rally, but it could reshape which industries benefit most.
Ultimately, the next stage of Wall Street’s performance will depend less on enthusiasm and more on whether companies can deliver the earnings growth already reflected in market expectations.
THE ABE TAKE
Wall Street’s current uncertainty reflects a fundamental tension between market expectations and business performance. Investors have rewarded companies for their growth potential, but increasingly demanding valuations require convincing evidence that those expectations can be achieved.
The strongest businesses may continue to perform well, even in a higher-interest-rate environment. However, strong companies do not automatically represent attractive investments at every price.
For investors, the distinction between a profitable company and a reasonably valued stock is becoming especially important. Earnings quality, cash flow, debt exposure and the ability to sustain investment deserve greater attention than market momentum alone.
For businesses, the message is equally significant. Capital is becoming more expensive, and investors are placing greater emphasis on financial discipline. Companies that can demonstrate sustainable profitability may be better positioned than those relying primarily on ambitious projections.
The coming earnings reports will not determine the market’s long-term future by themselves. They will, however, provide an important test of whether Wall Street’s recent gains are supported by the underlying strength of corporate America.
ABE MAGAZINE
Understand More. Think Bigger.