By ABE Magazine | November 3, 2026
Thomson Reuters reported stronger third-quarter revenue on Tuesday and raised its annual growth forecast. However, its shares declined as investors questioned the cost of expanding artificial intelligence products. The results highlight a growing challenge for technology companies: turning strong demand for AI into sustainable profitability.
The Toronto-based information and technology company generated US$1.83 billion in quarterly revenue, an increase of 10% from a year earlier. Its adjusted earnings reached 81 cents per share, up from 71 cents. The company also raised its forecast for organic revenue growth in 2026 to between 8.5% and 9%.
Despite the improvement, Thomson Reuters shares fell approximately 7% during trading on November 3. Investors appeared concerned that additional AI investment could limit future margin growth. The reaction shows that stronger sales do not always guarantee a positive response from financial markets.
Thomson Reuters Reports Stronger Third-Quarter Revenue
Thomson Reuters generated US$1.833 billion in revenue during the quarter ended September 30. That compares with US$1.658 billion in the same period last year. Both reported and organic revenue increased 10%, supported by demand across its professional information businesses.
Recurring revenue rose 9% to approximately US$1.62 billion. This category represented 88% of total company revenue. Transaction-related revenue increased 27%, providing an additional source of growth.
The company’s three largest customer segments also performed well. Legal Professionals generated US$788 million in revenue, an increase of 9%. The Corporates segment grew 11% to US$544 million, while Tax, Audit and Accounting Professionals increased 11% to US$276 million.
Together, these businesses generated approximately US$1.61 billion in quarterly revenue. Their combined organic growth reached 10%. The figures suggest that customers continue purchasing professional information, software and workflow services.
However, revenue growth tells only part of the financial story. Thomson Reuters must also manage the expenses associated with developing new products and maintaining its technology infrastructure. Those costs have become increasingly important as the company expands its AI capabilities.
Why Artificial Intelligence Is Central to the Company’s Strategy
Thomson Reuters serves professionals who depend on accurate information and efficient research tools. Its products support legal research, tax preparation, accounting, corporate compliance and business decision-making. These activities often involve large amounts of complex information.
Artificial intelligence offers opportunities to automate parts of that work. AI systems can help users locate relevant documents, summarize information and prepare initial drafts. They can also assist with tasks that previously required substantial manual research.
Thomson Reuters has placed its CoCounsel products at the centre of this strategy. The company is developing AI tools for legal, tax, audit and accounting professionals. These products aim to integrate AI assistance into existing professional workflows.
Chief executive Steve Hasker said customer engagement with the next generation of CoCounsel Legal had been encouraging. He also highlighted the recent launch of updated CoCounsel tools for tax, audit and accounting professionals. The company continues exploring commercial opportunities for its Thomson LLM technology.
The strategy reflects an important change in professional services. Customers increasingly expect software to help complete tasks rather than simply provide information. Companies that deliver reliable AI assistance may strengthen their relationships with users.
However, professional AI products face demanding requirements. Legal and financial work depends on accuracy, confidentiality and accountability. Thomson Reuters must demonstrate that its technology improves productivity without creating unacceptable risks.
Investors Question the Cost of AI Expansion
Thomson Reuters’ shares declined despite the company’s stronger financial results. Reuters reported that the stock fell about 7% as investors assessed the implications of higher AI spending. The market reaction reflected concerns about future profitability rather than an immediate decline in customer demand.
Developing AI products requires investment in software engineering, data infrastructure and specialized technology. Companies must also spend money on product testing, security and customer support. These costs can increase before new products generate substantial revenue.
For Thomson Reuters, the challenge is balancing innovation with financial discipline. Management wants to capture opportunities in professional AI software. Investors also expect the company to maintain attractive margins and generate cash.
Analyst Doug Arthur of Huber Research told Reuters that investors had expected steady margin improvement in 2027 and beyond. Additional investment opportunities could make that outlook less certain. The concern is not necessarily that AI investment lacks value, but that its financial benefits may take longer to emerge.
This debate extends across the technology industry. Companies are spending heavily on AI infrastructure and software development. Financial markets increasingly want evidence that those investments can produce measurable returns.
Profitability Shows a More Complicated Picture
Thomson Reuters reported US$402 million in operating profit for the third quarter. That represented a 22% decline from US$517 million a year earlier. The decrease partly reflected a gain recorded in the previous year from selling an investment in its former Elite business.
Higher software amortization also affected reported operating profit. This accounting expense reflects the allocation of certain software development costs over time. It does not necessarily represent a new cash payment during the quarter.
Adjusted EBITDA increased 10% to US$651 million. However, the adjusted EBITDA margin declined slightly to 35.5%, compared with 35.8% a year earlier. The company therefore generated more adjusted earnings before interest, taxes, depreciation and amortization, but at a marginally lower margin.
Adjusted earnings per share rose 14% to 81 cents. In contrast, reported diluted earnings per share declined to 78 cents from 94 cents. These different measures reflect the adjustments used in calculating underlying operating performance.
The distinction matters for investors. Adjusted figures can help explain ongoing business trends, but they do not replace reported financial results. A complete assessment requires examining both measures and understanding why they differ.
A Business Built on Recurring Revenue
One of Thomson Reuters’ financial strengths is its recurring revenue model. Many customers subscribe to professional software, research platforms and information services. These arrangements can provide greater revenue visibility than businesses that depend mainly on individual purchases.
Recurring revenue accounted for approximately 88% of the company’s quarterly total. That structure can support long-term customer relationships and predictable demand. It also creates opportunities to introduce additional products to existing clients.
The company’s legal research platform, Westlaw, remains an important part of its business. Tax and accounting services also support professionals who regularly need updated information and software. Corporate customers use its products for compliance, research and other operational tasks.
AI could strengthen this model if customers adopt more advanced services. A successful product may encourage users to upgrade subscriptions or purchase additional tools. However, the company must show that customers value those improvements enough to pay for them.
Competition presents another challenge. New AI-focused companies are developing products for legal and financial professionals. Thomson Reuters must continue improving its offerings while defending relationships with established customers.
Thomson Reuters Raises Its 2026 Revenue Forecast
Following the third-quarter results, Thomson Reuters increased its full-year organic revenue growth forecast to between 8.5% and 9%. Its previous outlook was approximately 8%. The company also expects total revenue growth of about 9.5%.
Management forecasts an adjusted EBITDA margin of approximately 39% for the year. These expectations reflect the company’s updated business structure following the sale of a majority stake in its Global Print division.
The company completed the sale of a 51% interest in that business to investment accounts advised by KKR on October 1. The transaction generated approximately US$500 million in gross proceeds. Thomson Reuters retained a minority interest.
The sale reflects a broader effort to concentrate resources on digital information and technology services. Print products remain relevant in some markets, but software and AI offer different growth opportunities. Management appears focused on expanding businesses that can serve customers through digital platforms.
Thomson Reuters also completed a US$600 million share repurchase programme announced earlier in 2026. In September, it issued approximately US$2 billion in debt securities. These financing decisions form part of the company’s wider capital management strategy.
However, stronger revenue guidance does not remove uncertainty over future margins. Additional AI investment could influence expenses and cash generation. Investors will continue examining how quickly the company’s spending produces commercial results.
Cash Flow Adds Another Consideration
Thomson Reuters generated US$599 million in operating cash flow during the quarter. That compares with US$704 million in the same period last year. The company attributed the decline partly to working capital changes and higher income tax payments.
Free cash flow fell to US$408 million from US$526 million. The decrease reflected lower operating cash flow and increased capital expenditure. These figures provide another perspective on the financial demands facing the business.
Cash flow matters because companies need financial resources to invest, repay debt and return capital to shareholders. Strong accounting earnings do not always translate into equally strong cash generation. Investors therefore examine how much cash remains after operating and investment expenses.
For Thomson Reuters, maintaining healthy cash flow will be important as AI development continues. The company must finance innovation while supporting existing products and customer relationships. Its ability to manage these competing demands could influence future investor confidence.
What the Results Mean for Canada’s Technology Sector
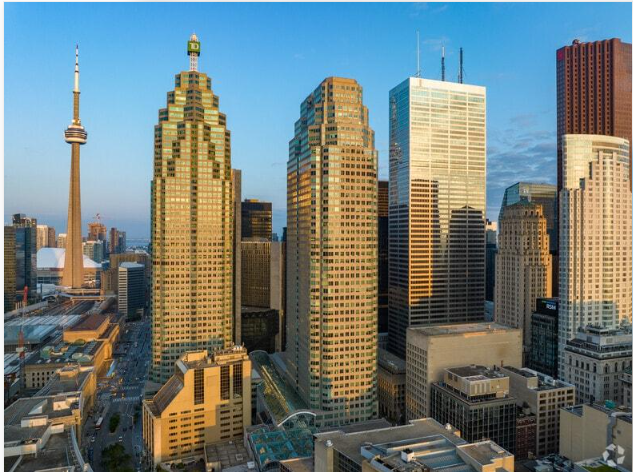
Thomson Reuters is one of Canada’s most prominent publicly traded information and technology companies. Its performance offers insight into how established businesses are adapting to artificial intelligence. Rather than building consumer-facing chatbots alone, the company is integrating AI into specialized professional services.
This approach could create opportunities for Canadian technology businesses. Industries such as legal services, accounting and corporate compliance depend on accurate information and complex workflows. Companies that understand these markets may find ways to develop valuable AI applications.
However, the financial challenges are significant. AI development requires technical expertise, capital and access to reliable data. Businesses must also meet customer expectations for security and accuracy.
Thomson Reuters’ results demonstrate that AI investment can coincide with strong revenue growth and investor concern. The company is expanding its products, but financial markets remain focused on profitability. This balance will become increasingly important across Canada’s technology sector.
The Wider Question Facing AI Businesses
The market reaction to Thomson Reuters reflects a larger debate about artificial intelligence investment. Companies are committing substantial resources to technologies they expect will transform business operations. Yet investors want to know when those investments will generate attractive financial returns.
The challenge differs across industries. Data-centre operators must finance physical infrastructure and computing equipment. Software companies invest in product development, engineering and customer adoption. Professional information providers must also maintain trusted databases and specialized content.
Thomson Reuters operates within this changing environment. Its established customer base and recurring revenue provide important advantages. However, those strengths do not guarantee that every AI investment will succeed.
The company’s future performance will depend on adoption, pricing and operating efficiency. Customers must find enough value in its AI products to justify continued spending. Management must also control development costs while maintaining product quality.
The next several quarters will help clarify whether stronger AI-related demand can support sustainable margin growth. Until then, investors are likely to remain sensitive to changes in spending expectations.
THE ABE TAKE
Thomson Reuters’ third-quarter results reveal an important contradiction in today’s technology industry. The company reported strong revenue growth and raised its annual forecast. Yet investors responded negatively because of concerns about future AI spending.
The reaction shows that financial markets are becoming more demanding. Companies can no longer rely solely on announcing new AI products or reporting strong customer interest. Investors increasingly want evidence that innovation will improve earnings and cash generation.
Thomson Reuters has meaningful advantages. Its professional information products serve established markets, and recurring revenue provides financial stability. The company also has opportunities to integrate AI into services customers already use.
However, successful technology development requires financial discipline. Higher spending may support future growth, but it can also pressure margins in the near term. Management must demonstrate that its investments create lasting value.
The next stage of the AI economy will not be defined only by which companies develop the most advanced technology. It will also depend on which businesses can turn that technology into reliable revenue, sustainable profits and long-term customer value.
ABE MAGAZINE
Understand More. Think Bigger.