









ABE NEWS | September 5, 2026
Two trillion dollars.
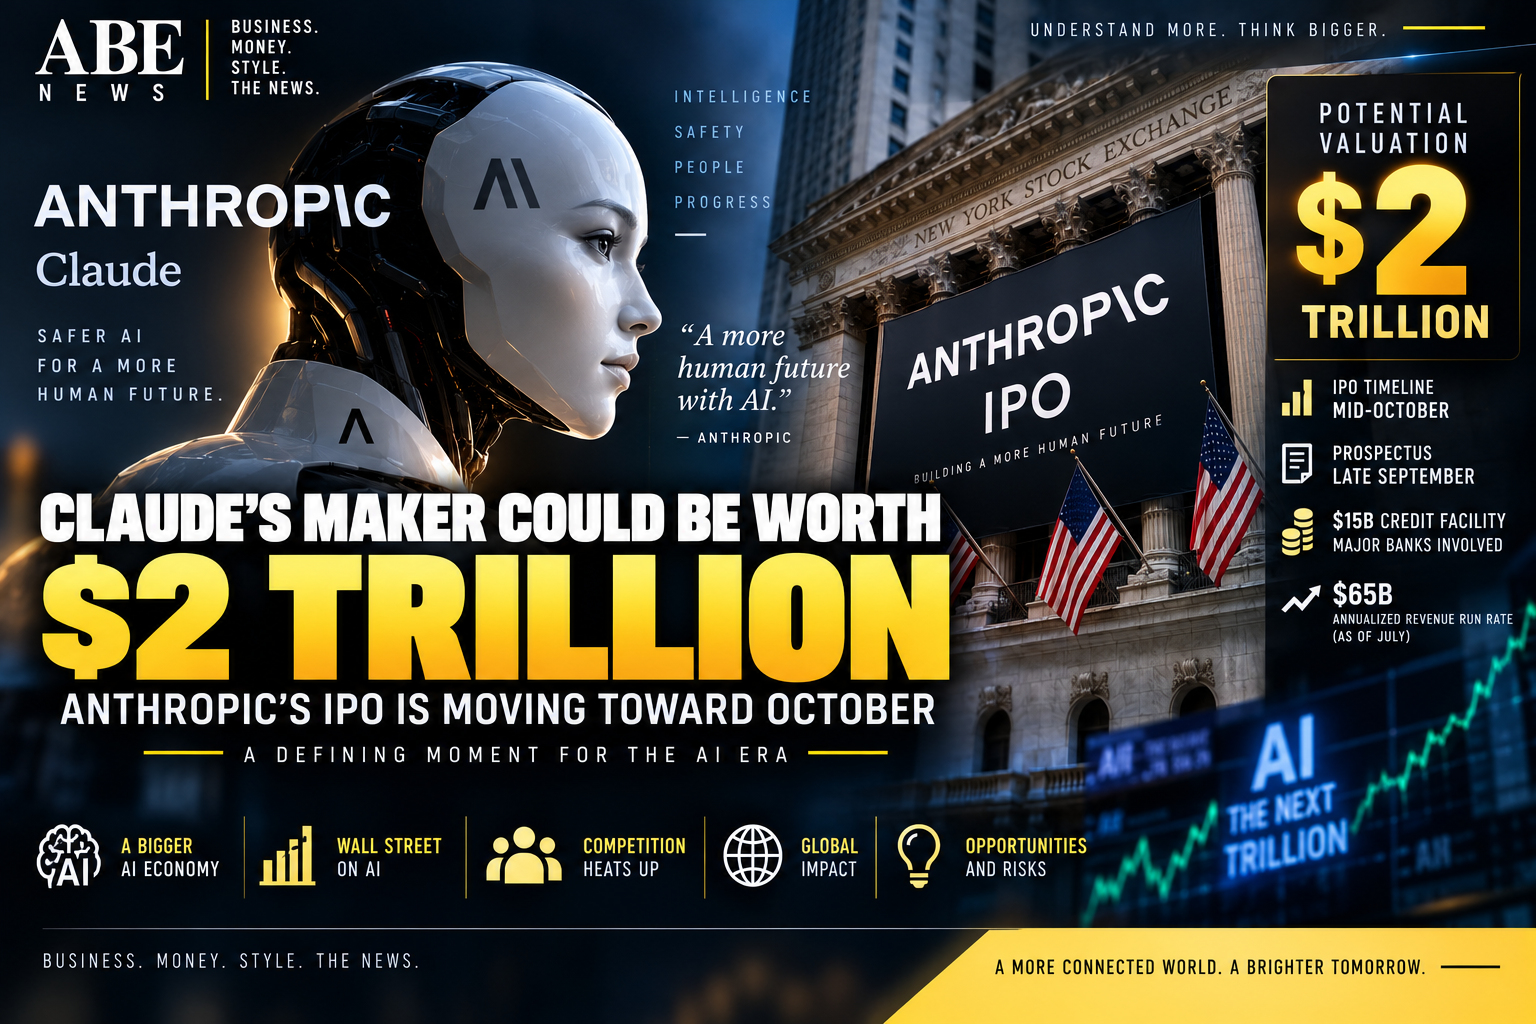
That is the extraordinary valuation Anthropic could potentially seek as the artificial-intelligence company behind Claude moves closer to one of the most consequential stock-market debuts in history.
Anthropic is now expected to begin marketing its initial public offering around mid-October, according to people familiar with the preparations.
The company’s prospectus, previously expected in early September, is now likely to arrive in late September.
And if current plans hold, Anthropic could complete its stock-market debut shortly before the U.S. midterm elections in November.
But the timetable isn’t what makes this IPO extraordinary.
The valuation is.
People familiar with the preparations say Anthropic could be valued at as much as $2 trillion.
That figure is not an officially announced target from Anthropic, and the final valuation could be lower.
But even discussing a $2 trillion valuation tells us how dramatically investor expectations surrounding artificial intelligence have changed.
Anthropic was founded only five years ago.
Now Wall Street is preparing for the possibility that it could enter the public markets with a valuation comparable to some of the largest corporations ever created.
The question investors will soon have to answer is simple:
Can Claude become valuable enough to justify it?
FROM AI STARTUP TO NEAR-TRILLION-DOLLAR PRIVATE COMPANY
Anthropic was founded in 2021 by former OpenAI employees, including siblings Dario and Daniela Amodei.
The company set out to build increasingly capable artificial-intelligence systems while emphasizing AI safety.
Its flagship product became Claude.
At first, Anthropic was one of several companies attempting to challenge OpenAI.
Then Claude began gaining serious traction.
Developers adopted it for coding.
Companies integrated it into workflows.
Businesses began paying for enterprise access.
Anthropic expanded its model capabilities.
And investors poured increasingly enormous amounts of money into the company.
By February 2026, Anthropic had reached a valuation of roughly $380 billion.
Then came another extraordinary jump.
In May, Anthropic raised $65 billion in a Series H financing round at a post-money valuation of approximately $965 billion.
That meant the company’s private valuation had more than doubled in only a few months.
Now, only months later, Wall Street is discussing the possibility of approximately $2 trillion.
THE GROWTH HAS BEEN EXTRAORDINARY
Why would investors even consider such a number?
Revenue growth.
Anthropic’s annualized revenue run rate surpassed $65 billion by the end of July, according to a person familiar with the company’s financial performance.
At the end of 2025, that figure was approximately $9 billion.
By May 2026, it had risen to roughly $47 billion.
Then approximately $65 billion by July.
That is extraordinary growth.
But there is an important distinction.
A revenue run rate is not the same thing as annual reported revenue.
It takes the company’s current revenue pace and extrapolates that performance over a full year.
If Anthropic’s current sales pace slowed, actual future annual revenue could be lower.
If it continued accelerating, it could be higher.
Still, the trajectory explains why investors are paying attention.
Claude has become a serious commercial product.
And one area in particular has helped drive that growth:
coding.
CLAUDE HAS BECOME A CODING POWERHOUSE
Artificial intelligence is changing software development rapidly.
Developers increasingly use AI to:
write code,
debug software,
explain unfamiliar systems,
build prototypes,
test applications,
review code,
and automate repetitive engineering work.
Claude has become particularly popular among developers.
That matters because professional software development is an enormous market.
Companies spend vast sums employing engineers and maintaining software systems.
If AI can meaningfully increase developer productivity, businesses may be willing to spend significant amounts on the technology.
Anthropic therefore isn’t merely competing for chatbot subscriptions.
It is trying to become infrastructure for knowledge work.
And coding may be one of the earliest markets where the economic value of frontier AI becomes clearly measurable.
WALL STREET IS LOOKING ALL THE WAY TO 2028
A $2 trillion valuation cannot be justified simply by today’s revenue.
Investors are looking much further ahead.
Reuters previously reported that Wall Street’s valuation models depend heavily on Anthropic potentially generating approximately $190 billion to $200 billion in annual revenue by 2028.
That would put Anthropic into an extraordinary corporate category.
For comparison, many globally recognized companies took decades to reach revenue measured in hundreds of billions of dollars.
Anthropic is asking investors to contemplate the possibility of getting there within years.
That is why this IPO could become one of the most important tests of the entire AI boom.
Public investors will effectively be asked to place an enormous bet on future earnings that do not yet exist.
THE $15 BILLION CREDIT FACILITY
Anthropic is also strengthening its financial position ahead of the IPO.
The company is finalizing a roughly $15 billion revolving credit facility, according to people familiar with the preparations.
Major banks involved include:
Morgan Stanley,
Goldman Sachs,
JPMorgan,
and Citi.
A revolving credit facility works somewhat like an enormous corporate credit line.
Anthropic doesn’t necessarily need to borrow the entire $15 billion immediately.
Instead, the facility provides access to capital when required.
That gives the company additional financial flexibility as it expands.
And Anthropic needs flexibility.
Because frontier AI is extraordinarily expensive.
BUILDING CLAUDE COSTS A FORTUNE
The consumer experience of artificial intelligence looks deceptively simple.
Open a website.
Type a question.
Receive an answer.
But behind Claude sit enormous amounts of physical infrastructure.
AI accelerators.
Servers.
Data centres.
Networking systems.
Cooling infrastructure.
Electricity.
Cloud-computing contracts.
Engineers.
Researchers.
Security teams.
And increasingly enormous long-term infrastructure commitments.
Anthropic’s success therefore creates a strange financial problem.
More customers can mean more revenue.
But serving those customers also requires significant computing resources.
That is fundamentally different from traditional software.
A conventional software company can sometimes add millions of users at relatively low marginal cost.
Frontier AI models require continuous computation every time users interact with them.
The economics can therefore be much more capital-intensive.
ANTHROPIC IS SPENDING ENORMOUSLY ON COMPUTING
The scale of the AI infrastructure race has become difficult to comprehend.
Anthropic has committed to enormous amounts of future computing capacity.
Reuters recently reported that the company plans to spend approximately $45 billion leasing AI cloud capacity from Nscale’s West Virginia data-centre campus.
Other enormous infrastructure projects are being developed around AI demand.
Anthropic has also entered major relationships with chip and cloud providers.
The company needs enough computing capacity to train future Claude models while simultaneously serving rapidly growing commercial demand.
That means the race between Anthropic, OpenAI, Google and other frontier laboratories is increasingly becoming a race for physical infrastructure.
And infrastructure costs money.
Lots of it.
THAT MAKES THE IPO ABOUT MORE THAN CASHING OUT
When companies go public, outsiders sometimes think the primary purpose is allowing founders and early investors to sell shares.
That can be part of an IPO.
But for an AI company, public markets offer something potentially more strategically important:
access to enormous amounts of capital.
A publicly traded Anthropic could issue additional shares.
Raise debt.
Use stock for acquisitions.
Offer equity compensation.
And potentially finance data centres and computing commitments on a scale difficult for most private companies.
That matters when your competitors include companies backed by some of the deepest pockets on Earth.
ANTHROPIC IS FIGHTING GIANTS
Claude does not operate in an empty market.
Anthropic competes directly or indirectly with:
OpenAI,
Google,
Meta,
Microsoft,
xAI,
Chinese AI laboratories,
and increasingly specialized model companies around the world.
Several of those competitors possess enormous structural advantages.
Google generates billions from Search, YouTube and advertising.
Meta generates billions from Facebook and Instagram.
Microsoft generates enormous cash flows from enterprise software and cloud computing.
Amazon owns AWS.
These companies can use profits from existing businesses to finance AI.
Anthropic doesn’t have that luxury.
Its core business is AI.
That makes access to outside capital particularly important.
AMAZON AND GOOGLE ARE ALREADY DEEPLY INVOLVED
Anthropic’s position is unusual because two major technology companies have already become strategically important partners.
Amazon has invested heavily in Anthropic and made Claude an important part of its AWS AI offering.
Google has also invested in the company and provides computing infrastructure.
That creates an interesting competitive web.
Google develops Gemini.
Amazon distributes multiple AI models.
Anthropic develops Claude.
Yet these companies can simultaneously compete and cooperate because the AI ecosystem is so capital-intensive.
A public listing could give Anthropic greater independence by opening another enormous source of capital.
THEN THERE’S OPENAI
Anthropic’s IPO cannot be understood without its biggest rival.
OpenAI has also confidentially filed for a U.S. IPO.
That means Wall Street could potentially receive access to both Claude and ChatGPT within a relatively short period.
This would be extraordinary.
For years, ordinary investors watched the generative-AI boom largely from the sidelines.
They could buy Nvidia.
Microsoft.
Alphabet.
Amazon.
Meta.
But they couldn’t directly own shares in OpenAI or Anthropic.
That may soon change.
And if both companies reach public markets, investors will begin making direct comparisons.
Claude versus ChatGPT.
Revenue growth.
Margins.
Enterprise customers.
Developer adoption.
Computing costs.
Model performance.
Capital spending.
And eventually:
profits.
SPACEX HAS ALREADY CHANGED WHAT INVESTORS THINK IS POSSIBLE
Earlier this year, SpaceX provided Wall Street with an extraordinary demonstration of investor appetite for transformational technology companies.
SpaceX completed a record-setting $75 billion IPO.
Its shares then surged during their Nasdaq debut, pushing the company’s market value beyond $2 trillion.
That matters for Anthropic.
Before SpaceX, a $2 trillion IPO valuation for a company with unusual economics might have sounded almost impossible.
Now Wall Street has seen investors enthusiastically embrace one.
But there is an important difference.
SpaceX has Starlink.
Rockets.
Government contracts.
Satellite infrastructure.
Physical assets.
And years of operating history.
Anthropic is much younger.
Its valuation would depend far more heavily on expectations about how rapidly AI becomes embedded across the global economy.
THE $2 TRILLION QUESTION
Suppose Anthropic reaches the public market at a $2 trillion valuation.
What exactly are investors buying?
Not merely Claude today.
They are buying a theory about Claude tomorrow.
A theory that AI becomes deeply integrated into business.
That companies spend enormous amounts on AI agents.
That developers increasingly rely on Claude.
That enterprises automate knowledge work.
That model capabilities continue improving.
That Anthropic remains one of the industry’s leaders.
That competitors don’t destroy pricing power.
That computing costs become manageable.
That regulation doesn’t derail growth.
And ultimately:
that Anthropic converts extraordinary revenue growth into extraordinary profits.
That is a lot of assumptions embedded inside one valuation.
$200 BILLION OF REVENUE WOULD STILL NEED PROFITS
Revenue is impressive.
Profit matters more.
AI companies face enormous infrastructure expenses.
If Anthropic generates $200 billion of annual revenue but must spend enormous amounts serving those customers and training increasingly expensive models, the economics may look very different from a traditional software company.
Investors will therefore pay close attention to gross margins.
How much does Anthropic spend generating each dollar of revenue?
How quickly are inference costs falling?
How expensive are future models to train?
How much infrastructure must be leased?
How dependent is Anthropic on external cloud providers?
Those questions may eventually matter more than benchmark scores.
The stock market rewards growth.
But over time, it rewards cash.
THIS COULD BE THE ULTIMATE AI-BUBBLE TEST
The word “bubble” has followed artificial intelligence for years.
Critics argue valuations have outrun economic reality.
Supporters argue AI is a technological platform comparable to the internet, electricity or the Industrial Revolution.
Anthropic’s IPO could force those competing views into the same marketplace.
If investors eagerly value the company near $2 trillion, it would demonstrate extraordinary confidence that AI revenues and profits will eventually justify today’s infrastructure spending.
If investors push back, it could signal that enthusiasm has limits.
That makes Anthropic’s IPO bigger than Anthropic.
It could become a referendum on the valuation of artificial intelligence itself.
THE TIMING IS POLITICALLY INTERESTING TOO
According to Reuters, Anthropic is now expected to begin marketing the IPO around mid-October.
The listing could then conclude shortly before America’s November midterm elections.
That places one of the largest potential IPOs in history directly inside an intense political period.
Artificial intelligence is already becoming a major political issue.
Jobs.
Copyright.
Energy consumption.
Data centres.
National security.
China.
Military applications.
Regulation.
AI safety.
All of those debates could intersect with Anthropic’s public-market debut.
The company itself has already been involved in disputes over how AI should be used in sensitive government and military contexts.
Going public would expose those debates to an entirely new audience:
shareholders.
PUBLIC MARKETS CHANGE COMPANIES
Private companies can operate with significant flexibility.
Quarterly earnings aren’t public spectacles.
Analysts don’t interrogate management every three months.
Share prices don’t move every time a competitor launches a new product.
Public companies live differently.
Anthropic would need to disclose far more financial information.
Investors would scrutinize spending.
Margins.
Growth.
Customer concentration.
Risks.
Executive compensation.
Infrastructure commitments.
Legal disputes.
And eventually profitability.
That could be healthy.
AI companies have become enormously influential while remaining relatively opaque financially.
An IPO would expose much more of the economics behind frontier AI.
And those economics may tell us more about the industry’s future than any benchmark leaderboard.
🔴 THE ABE NEWS TAKE
Forget the $2 trillion number for a moment.
The most important thing about Anthropic’s IPO is what it represents.
Artificial intelligence is moving from venture capital to public capitalism.
For years, the biggest bets on frontier AI were made by private investors and giant technology companies.
Amazon could invest billions.
Google could invest billions.
Venture funds could invest.
Institutional investors could participate in private rounds.
Ordinary public-market investors largely watched from outside.
Now that wall is beginning to fall.
Anthropic is preparing to enter the stock market.
OpenAI has filed too.
And Wall Street may soon be asked to price the companies building some of the most important technology of this generation.
That’s when the conversation changes.
Private investors can tolerate extraordinary uncertainty in exchange for extraordinary potential.
Public markets eventually demand numbers.
Revenue.
Margins.
Cash flow.
Capital expenditure.
Debt.
Profit.
Anthropic’s growth has been astonishing.
Its annualized revenue run rate reportedly rose from around $9 billion at the end of 2025 to more than $65 billion by the end of July.
That helps explain why anyone is even discussing $2 trillion.
But extrapolating extraordinary early growth indefinitely is dangerous.
The $190 billion to $200 billion 2028 revenue projections underlying some Wall Street valuation models still need to become reality.
Then those revenues need to produce enough profit to justify the valuation.
And Anthropic must accomplish all of this while competing with OpenAI, Google, Meta and some of the richest companies in corporate history.
That’s what makes this IPO fascinating.
If Anthropic approaches $2 trillion, investors won’t simply be buying an AI company.
They’ll be buying a belief:
That Claude and systems like it will become infrastructure for the global economy.
That AI agents will become digital workers.
That businesses will spend hundreds of billions of dollars on intelligence delivered through software.
And that Anthropic will capture a meaningful portion of that value.
Maybe they’re right.
If AI becomes as economically important as its strongest advocates predict, today’s valuation may eventually look understandable.
But if competition commoditizes models, infrastructure costs remain enormous or AI revenues fail to translate into profits, $2 trillion could look very different in hindsight.
That is why Anthropic’s IPO could become one of the defining financial events of the AI era.
Not because of how much money the company raises.
Not because Claude is popular.
And not even because $2 trillion is an extraordinary number.
But because for perhaps the first time, millions of public investors may soon have to answer the question venture capitalists have been betting billions on for years:
What is frontier artificial intelligence actually worth?
Wall Street may be about to give us an answer.
ABE NEWS
Business. Money. Style. The News.
Understand More. Think Bigger.



