ABE MAGAZINE | ABE FOUNDERS
October 24, 2026
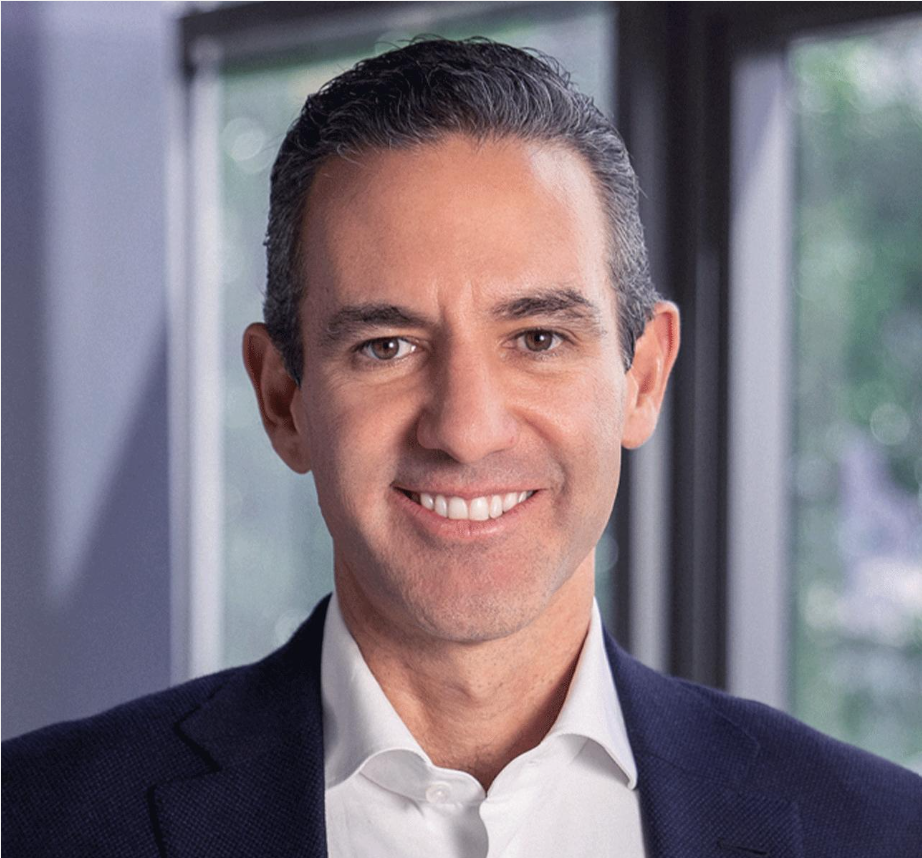
Some entrepreneurs enter an industry because they understand its opportunities. Others discover those opportunities through frustration. For David Vélez, the journey toward building Nubank began with an experience that millions of banking customers could recognize: complicated procedures, excessive fees and a financial system that seemed more interested in protecting established institutions than serving ordinary people. What followed was an ambitious attempt to rethink banking in Latin America, transforming a personal inconvenience into one of the region’s most significant business success stories.
A Frustrating Experience That Revealed an Opportunity
When Colombian-born entrepreneur David Vélez arrived in Brazil, he encountered an unexpected obstacle. Opening a bank account, something that should have been a straightforward financial transaction, became a lengthy and frustrating process involving repeated visits, extensive documentation and considerable waiting. For many customers, such experiences were simply an accepted part of banking. For Vélez, they raised a different question: why had an industry generating enormous profits become so difficult for its customers to navigate?
Brazil’s banking sector was dominated by powerful financial institutions with established branch networks, substantial resources and longstanding customer relationships. Entering such a market would be challenging for almost any entrepreneur, particularly one proposing to operate without the traditional infrastructure that had defined banking for generations. Yet Vélez recognized that technological changes, especially the growing adoption of smartphones, were creating opportunities to serve customers differently.
His insight was not that people no longer needed banking services. They still needed payments, credit, savings and reliable financial support. The opportunity was to change how those services were delivered, removing unnecessary complexity and making the customer experience central to the business.
Building a Company Against Conventional Expectations
In 2013, Vélez founded Nubank alongside Cristina Junqueira and Edward Wible. Each brought different expertise to the venture. Vélez contributed investment experience and a broader commercial vision, Junqueira understood the Brazilian banking industry and its customers, while Wible provided the engineering knowledge required to develop a digital financial platform.
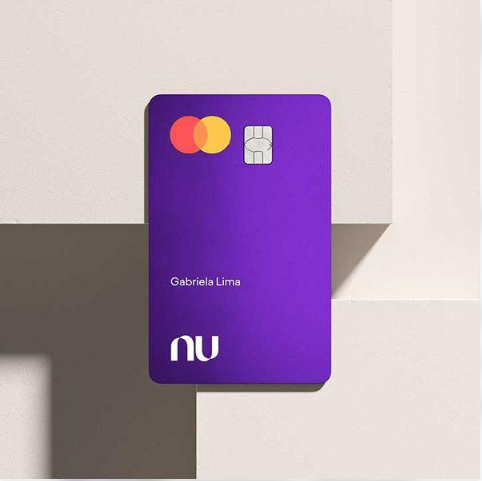
Their ambition was considerable, but the company’s initial proposition was relatively simple: a credit card without the annual fees traditionally associated with many banking products, managed through a mobile application. Customers could apply without visiting a branch, monitor their accounts digitally and communicate with support teams through modern channels.
This approach challenged more than the pricing structures of established banks. It challenged the assumption that financial services required expensive physical networks and complicated administrative processes. Nubank sought to demonstrate that technology could reduce operating costs while improving accessibility and convenience.
The company also faced considerable scepticism. Banking was heavily regulated, customer trust was difficult to establish and competitors possessed advantages accumulated over decades. Convincing investors that a new digital financial institution could compete with established banks required persistence. Convincing customers to trust an unfamiliar company with their financial lives presented an equally important challenge.
Why Customer Experience Became a Competitive Advantage
One of Nubank’s defining decisions was to treat customer experience as a fundamental business strategy rather than an additional service. Traditional banks often relied on the difficulty of switching providers and the strength of their existing relationships. Nubank instead attempted to attract customers through simplicity, transparency and a more accessible digital experience.
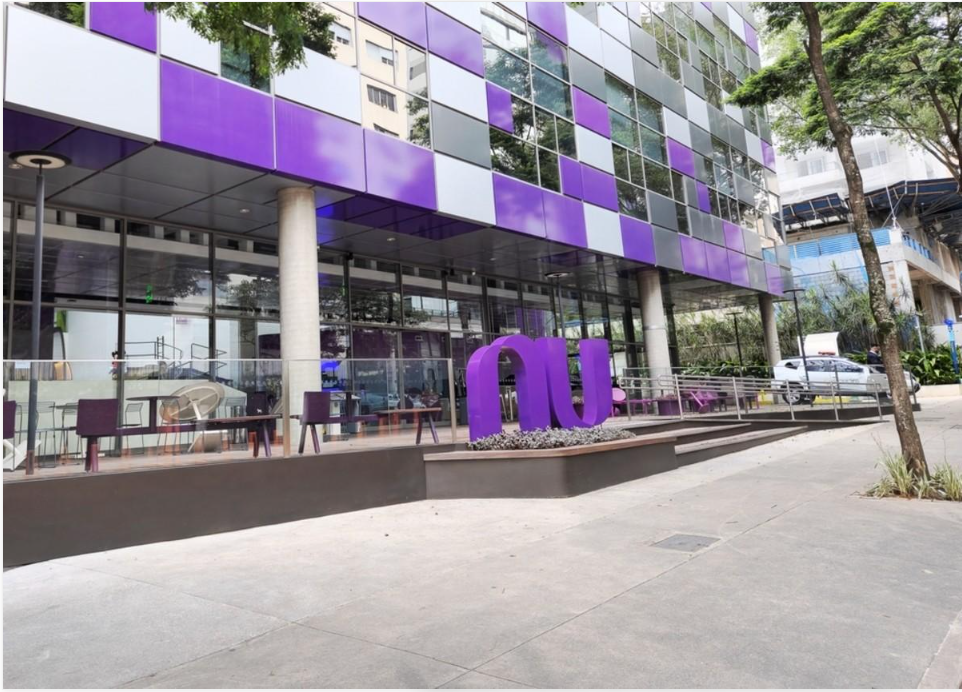
The company’s distinctive purple branding also helped establish an identity that differed from the conservative appearance traditionally associated with financial institutions. However, branding alone would not have been sufficient. The company’s early growth depended on whether customers believed its services genuinely addressed the problems they experienced with existing providers.
As Nubank attracted more customers, its business model demonstrated the potential of digital distribution. Without maintaining a conventional branch network, the company could reach consumers through mobile technology while developing additional financial products. Over time, its offerings expanded beyond credit cards to include accounts, payments, lending and services for businesses.
The underlying lesson was that a company does not always need to invent an entirely new product category to create meaningful change. Sometimes, improving an existing service can become the foundation of a powerful competitive position.
From a Brazilian Startup to a Regional Financial Institution
Nubank’s expansion required the company to move beyond the advantages of its original product. Serving millions of customers demanded stronger infrastructure, more sophisticated risk management, regulatory compliance and the ability to maintain service quality at scale.
The company eventually expanded into Mexico and Colombia, taking its digital banking approach into markets with their own financial regulations, consumer expectations and competitive conditions. Such expansion brought opportunities but also introduced new risks. Financial services companies cannot simply replicate a product across borders without accounting for local economic realities and legal requirements.
By the second quarter of 2026, Nubank reported approximately 139 million customers across its markets, demonstrating the extraordinary scale achieved since its founding. The company also reported quarterly net income exceeding $1 billion, illustrating its evolution from a venture-backed challenger into a large and profitable financial institution.
These achievements, however, do not eliminate the challenges associated with banking. Credit losses, economic uncertainty, competition and regulatory requirements remain important considerations. For a company built on simplifying financial services, maintaining that promise becomes increasingly demanding as the organization grows.
The Founder Behind the Business Decisions
Vélez’s story is often presented as an example of technological disruption, but it also reflects the importance of judgment. Identifying an inefficient market was only the beginning. He needed to assemble a capable founding team, secure financing, build customer trust and navigate an industry where mistakes could carry serious financial consequences.
His earlier experience in investment banking and venture capital provided useful exposure to business models, financial analysis and company building. Yet that experience did not guarantee Nubank’s success. The venture still required a willingness to challenge accepted assumptions while recognizing that banking could not operate without financial discipline.
One particularly important aspect of his journey is the distinction between confidence and certainty. Entrepreneurs rarely possess complete information about how a market will respond to a new idea. They must evaluate the evidence available, understand the risks and make decisions despite uncertainty. Vélez’s decision to enter banking reflected conviction in an opportunity, but the company’s development depended on turning that conviction into products customers would actually use.
THE ABE TAKE: An Opportunity Can Hide Inside an Accepted Problem
David Vélez’s entrepreneurial journey demonstrates that business opportunities are sometimes concealed within experiences that people have stopped questioning. Long queues, confusing procedures and expensive services may appear to be unavoidable features of an established industry. Yet those frustrations can reveal weaknesses that innovative businesses are capable of addressing.
For aspiring entrepreneurs, the lesson is not simply to challenge large corporations. It is to understand precisely why customers are dissatisfied and determine whether a better solution can be delivered sustainably. A promising idea must eventually become a viable business model, supported by operational discipline, effective leadership and a clear understanding of the market.
Nubank’s story also shows that customer experience and commercial success need not be competing priorities. When a business genuinely makes an important service simpler and more accessible, that improvement can become a source of long-term differentiation.
Perhaps the most valuable lesson from Vélez’s journey is that familiarity should never be confused with efficiency. An industry may operate in a particular way for decades without that approach being the best possible solution. Entrepreneurs who question those assumptions, while remaining realistic about the risks, can discover opportunities that others overlook.
ABE MAGAZINE
Understand More. Think Bigger.