By ABE Magazine
In 2020, as the COVID-19 pandemic disrupted businesses across the world, two entrepreneurs in Berlin began building a financial technology company designed to simplify how businesses make payments.
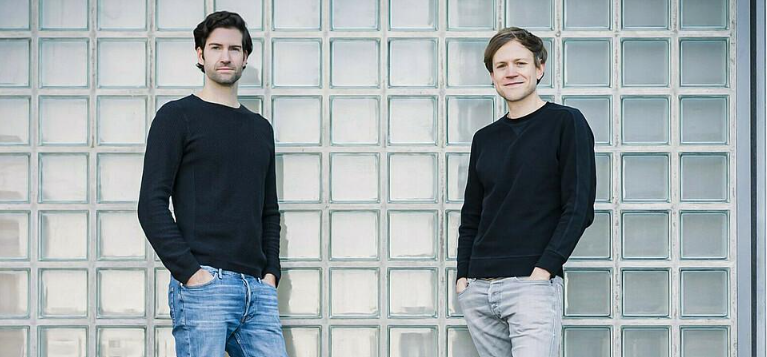
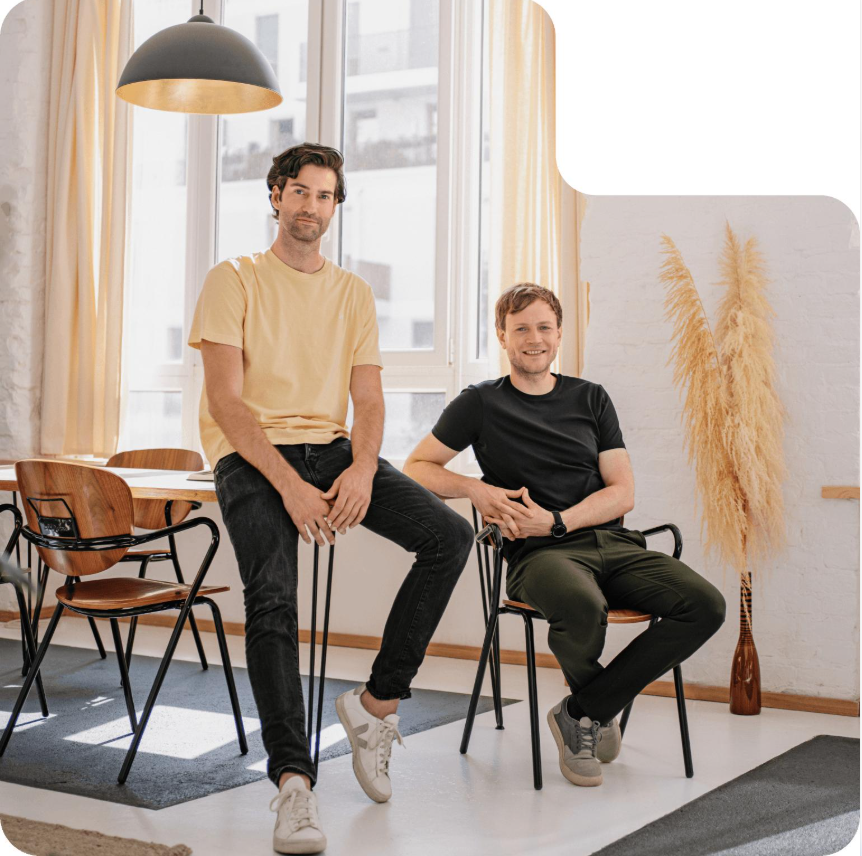
Malte Rau and Fabian Terner founded Pliant with a relatively straightforward idea: corporate payments were unnecessarily complicated, and businesses needed more flexible ways to manage spending.
Six years later, the company has grown from a startup offering corporate credit cards into an international payments infrastructure provider.
On November 4, 2026, Pliant announced an $80 million Series C funding round led by Seaya Nova and Speedinvest. The company also reported surpassing $100 million in annual recurring revenue, marking an important milestone in its expansion.
But Pliant’s development reveals more than a successful fundraising story. It demonstrates how a business can enter an established financial industry by solving a specific operational problem before expanding into a much larger market.
Starting a Financial Company During a Crisis
Launching a financial technology business in 2020 was particularly challenging.
The pandemic disrupted normal business activity, investment conditions were uncertain, and Germany’s financial sector was shaken by the collapse of payments company Wirecard.
For Pliant, the Wirecard scandal created an immediate operational problem. Wirecard had been expected to provide the infrastructure necessary to issue the company’s cards.
In a February 2026 interview with FinTech Futures, Rau explained that Visa helped the young business identify another issuing partner after Wirecard’s failure.
That relationship became important in allowing Pliant to continue developing its products.
Rather than attempting to become a traditional bank, the founders concentrated on creating better payment tools for businesses.
Their initial offering included corporate credit cards, digital spending controls and integrations with financial software.
The approach targeted a practical problem: many companies relied on fragmented systems for employee spending, receipts, payments and accounting.
Building Around an Existing Business Problem
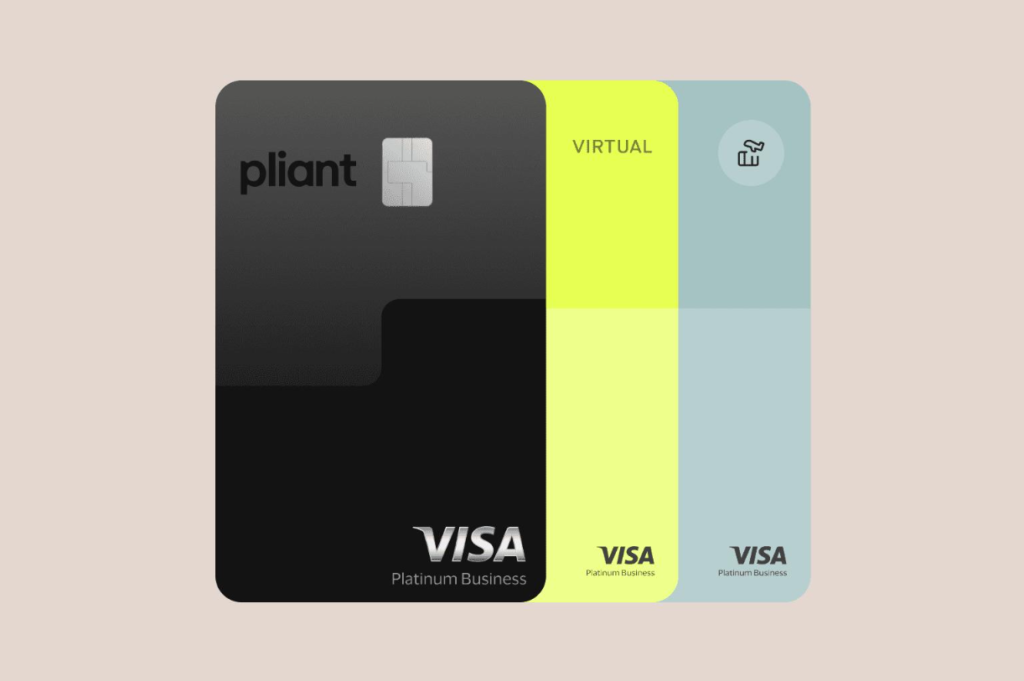
Pliant’s early strategy focused on improving the experience of corporate payments.
Businesses could issue physical and virtual cards, establish spending limits and integrate transaction information into accounting systems.
The company later expanded beyond serving businesses directly.
It began providing infrastructure that banks, fintech companies and software providers could use to launch their own commercial payment products.
This created two complementary opportunities.
Pliant could earn revenue from companies using its payment services while also supporting financial institutions that wanted to offer similar capabilities to their own customers.
The infrastructure model helped position Pliant as more than another corporate card provider.
Instead of competing only through the cards it issued, the company increasingly competed through the technology and financial infrastructure behind those cards.
From Startup Funding to International Expansion
Pliant’s expansion was supported by several major investment rounds.
In February 2023, the company raised $28 million in Series A funding. In April 2025, it announced a further $40 million Series B round to support its entry into the United States.
The latest $80 million Series C investment marks another stage in that development.
According to the company’s November 2026 announcement, Pliant has more than 300 employees across eight offices and processes billions of dollars in annual payment volume.
Its customers and partners operate across industries including travel, insurance, banking and financial technology.
The company has also expanded its international presence, issuing commercial cards in 13 currencies across 32 countries through its regulated infrastructure and partners.
However, its reported revenue milestone does not necessarily indicate profitability. Annual recurring revenue measures the recurring revenue base rather than the amount of profit a company earns.
That distinction is important when assessing the financial performance of a rapidly expanding startup.
The Next Opportunity: Payments Made by Artificial Intelligence
Pliant’s latest funding round also reveals where its founders believe the payments industry is heading.
As artificial intelligence systems become capable of completing more business tasks, companies are exploring whether software agents can initiate and manage financial transactions.
Pliant wants to provide the infrastructure that allows these systems to interact with payment services while maintaining permissions, spending controls and auditability.
Its platform already supports automation of recurring financial tasks, and the company plans to expand its capabilities for external AI agents.
The commercial opportunity is significant, but so are the risks.
Payments initiated by automated systems raise questions about authorization, fraud prevention, accountability and financial regulation.
For Pliant, the challenge will be proving that automation can make payments more efficient without weakening the controls that businesses and regulators require.
Competition Will Be a Major Test
Pliant is entering a market where established payment networks, banks and other financial technology companies are also investing in automation.
Companies such as Stripe, Ramp and other corporate payments providers are developing increasingly sophisticated financial platforms.
Pliant’s competitive advantage may depend on its ability to combine regulated payment infrastructure with flexible technology that other businesses can integrate into their own systems.
Its expansion into North America will also require navigating different regulatory requirements and customer expectations.
Strong revenue growth and substantial investment capital provide resources for expansion, but they do not guarantee that the company will become a dominant global payments provider.
Its long-term performance will depend on customer adoption, product reliability, regulatory compliance and the economics of its business model.
THE ABE TAKE
Pliant’s story illustrates an important principle of entrepreneurship: successful companies do not always begin by attempting to transform an entire industry.
Sometimes they begin by identifying one inefficient process and developing a better solution.
Rau and Terner started with corporate payment cards, but their broader opportunity emerged from the infrastructure required to make those cards useful.
That evolution allowed Pliant to move from offering a financial product to providing technology that other financial businesses could build upon.
The company’s latest investment suggests that its backers see another potential transformation in the relationship between software and money.
However, the most important measure of Pliant’s success will not be the amount of capital it raises. It will be whether its infrastructure becomes sufficiently useful, reliable and trusted to support long-term business activity.
For entrepreneurs, the lesson is clear: solving a specific problem can create opportunities far beyond the original product, provided the business continues to develop around genuine customer needs.
ABE MAGAZINE
Understand More. Think Bigger.