By ABE Magazine | November 4, 2026
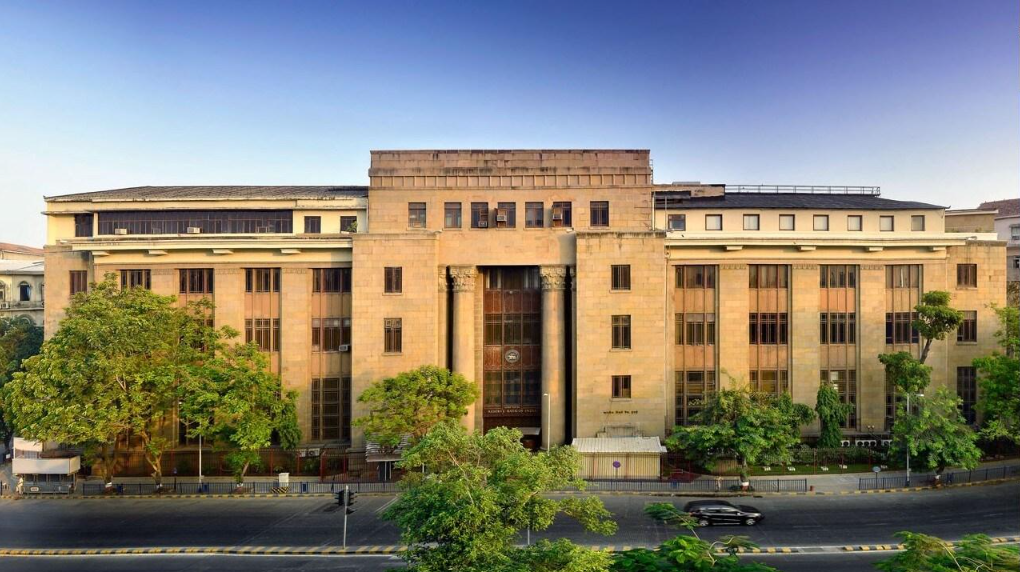
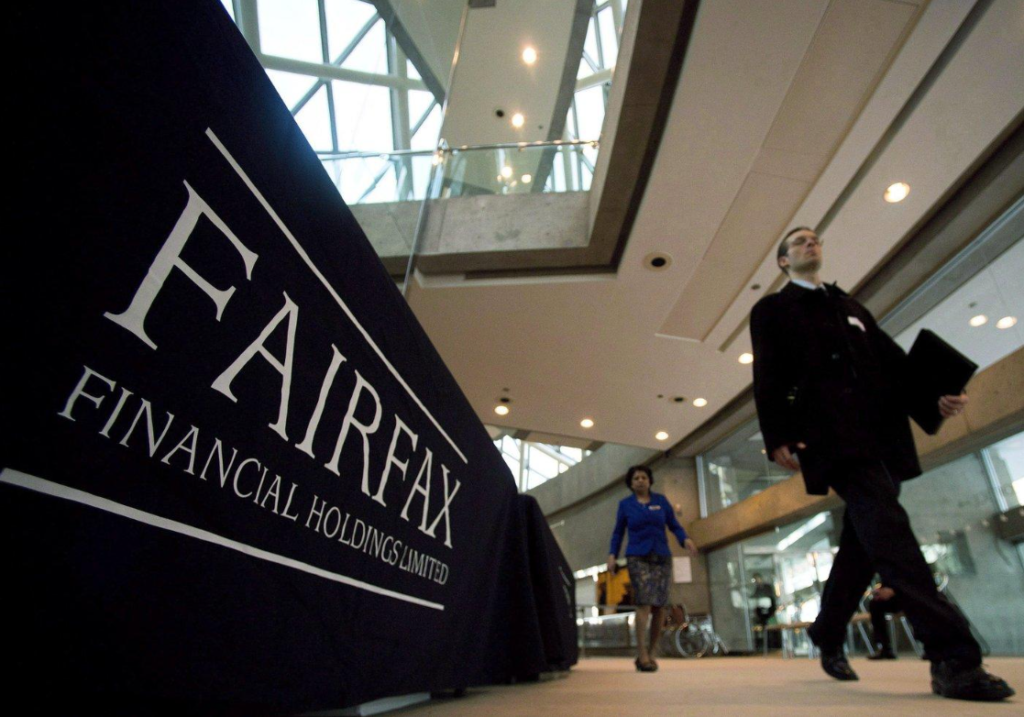
Canadian financial services company Fairfax Financial Holdings is facing growing opposition to its proposed $5.5 billion acquisition of a controlling stake in India’s IDBI Bank, as employee groups and political critics raise concerns about the privatization of a major financial institution.
The proposed transaction would give Toronto-based Fairfax control of approximately 60.7% of IDBI Bank, marking a significant expansion of its banking interests in India. However, the deal has become politically sensitive because it involves the transfer of a government-linked bank into private ownership, raising questions about employment, public accountability and the future of India’s banking sector.
The dispute highlights a broader challenge facing governments around the world: how to attract private investment into financial institutions while protecting depositors, employees and the public interest.
A Canadian Financial Group Pursues a Major Indian Bank
Fairfax Financial Holdings is an international insurance and investment company headquartered in Toronto. Founded by Canadian businessman Prem Watsa, the group has built a portfolio of insurance businesses and investments across several international markets.
India has become an important part of Fairfax’s investment strategy, with the company maintaining interests in financial services and other industries.
Its proposed acquisition of IDBI Bank represents a particularly ambitious transaction because banking differs significantly from many other forms of corporate investment. Banks accept deposits, provide credit, process payments and support economic activity, making their ownership and management matters of public concern.
The transaction involves a controlling stake of approximately 60.7%, currently associated with the Indian government and the state-controlled Life Insurance Corporation of India.
A successful acquisition would give Fairfax significant influence over IDBI Bank’s management, strategic direction and future expansion.
However, the proposed transaction remains subject to the relevant regulatory and transaction requirements. Opposition to the sale has added uncertainty about how smoothly the process can proceed.
Why India Wants to Privatize IDBI Bank
India has spent years discussing the role of government ownership in its banking system.
Public-sector banks have historically played an important part in financing businesses, supporting economic development and expanding access to financial services. However, government ownership can also create challenges involving political influence, operational efficiency and the allocation of capital.
Privatization is intended to introduce private ownership and potentially improve management, profitability and competitiveness.
Supporters argue that private investors may bring stronger commercial incentives, modern technology and additional capital to financial institutions.
They also believe that selling government stakes can release public resources for other priorities while reducing the state’s direct involvement in commercial banking.
However, these arguments depend on the quality of the buyer, the terms of the transaction and the effectiveness of financial regulation.
Private ownership does not automatically guarantee better management. Banks can experience serious financial problems regardless of whether their shareholders are governments or private investors.
For India, the challenge is determining whether the proposed sale will improve IDBI Bank’s long-term performance without weakening confidence in the banking system.
Employees Protest the Proposed Acquisition
Opposition to the Fairfax transaction has emerged from employee organizations concerned about the consequences of privatization.
Workers have raised questions about job security, employment conditions and the possibility of organizational restructuring under new ownership.
These concerns are particularly important in banking because mergers and acquisitions can lead to changes in branch networks, technology systems and staffing requirements.
A new controlling shareholder may seek to improve efficiency by reorganizing operations, introducing digital services or reducing overlapping functions.
Such changes can strengthen financial performance, but they can also create uncertainty for employees.
Political opposition has added another dimension to the dispute. Critics question whether a major banking institution should move from public-linked ownership into private hands and whether the proposed sale adequately protects national economic interests.
Supporters of privatization, meanwhile, argue that ownership changes should be judged by their economic outcomes rather than by whether the buyer is private or public.
The debate demonstrates that major bank acquisitions involve more than financial negotiations between shareholders. They can affect employees, borrowers, depositors and the wider economy.
What Fairfax Could Gain From the Acquisition
India offers substantial long-term opportunities for banking investors.
Its large population, expanding digital payments infrastructure and growing demand for financial services create opportunities for banks that can attract deposits, provide credit and develop competitive products.
A controlling interest in IDBI Bank would give Fairfax access to an established financial institution rather than requiring it to build a nationwide banking operation from the beginning.
Existing branches, customers, regulatory relationships and banking infrastructure can provide an important foundation for expansion.
However, acquiring an established bank also means inheriting its operational responsibilities and potential weaknesses.
Fairfax would need to evaluate credit quality, capital requirements, operating costs and the bank’s competitive position.
The success of the investment would ultimately depend on whether the company can improve the institution’s performance while maintaining regulatory compliance and customer confidence.
A large acquisition price alone does not establish that a transaction will create value.
Why Banking Acquisitions Are Different From Ordinary Corporate Deals
Banks occupy a distinctive position in the economy because they manage money entrusted to them by depositors.
When an investor acquires a manufacturing company, the transaction primarily affects its owners, employees, suppliers and customers. A bank acquisition introduces additional considerations involving financial stability, credit availability and the safety of deposits.
Banks operate under capital and liquidity requirements designed to reduce the risk of failure.
Regulators also examine ownership structures and management arrangements because financial institutions can create wider economic problems if they become unstable.
For this reason, acquiring a controlling stake in a bank typically requires more extensive scrutiny than buying an ordinary commercial business.
The Fairfax–IDBI transaction must therefore be evaluated not only for its purchase price but also for the buyer’s ability to manage a regulated financial institution responsibly.
An important distinction is that privatization does not eliminate government oversight. Even privately owned banks remain subject to banking regulations and supervisory authorities.
The question is whether the new ownership structure can deliver better performance while preserving the safeguards expected of a major financial institution.
India’s Banking Sector Is Becoming More Competitive
India’s financial services market has undergone substantial changes as digital banking and electronic payments have expanded.
Traditional banks increasingly compete with technology-driven financial services companies offering convenient payment systems, mobile applications and other digital products.
This transformation creates opportunities for institutions that can modernize their services and operate efficiently.
However, technological expansion also introduces risks involving cybersecurity, fraud, customer protection and operational resilience.
Established banks must invest in secure digital infrastructure while maintaining their existing responsibilities to depositors and borrowers.
For a potential investor such as Fairfax, improving technology could form part of a longer-term strategy to strengthen IDBI Bank’s competitive position.
Yet technology investment requires capital, effective management and careful implementation.
The broader lesson is that banking competitiveness increasingly depends on more than branch networks and traditional lending. Digital infrastructure, customer trust and risk management are becoming equally important.
What the Deal Means for Canada
Although the acquisition concerns an Indian bank, its implications extend to Canada’s international financial sector.
Fairfax is a Canadian-headquartered company with substantial overseas investments. A successful transaction would reinforce the role of Canadian capital in international financial services.
Canada’s major banks already operate in foreign markets, although their international strategies differ considerably.
Fairfax’s approach demonstrates another route to global financial expansion: using an investment and insurance group to acquire significant interests in established businesses abroad.
However, international expansion creates exposure to foreign regulations, political developments, currency movements and local economic conditions.
The IDBI Bank dispute illustrates why those risks matter.
Even when an acquisition appears financially attractive, public opposition and regulatory requirements can influence whether the transaction proceeds as expected.
Canadian investors considering overseas opportunities must therefore assess political and institutional risks alongside financial returns.
The Political Risks of Bank Privatization
The opposition surrounding IDBI Bank reflects a longstanding debate over public ownership of essential financial institutions.
Supporters of privatization argue that governments should concentrate on regulation and public services rather than directly managing commercial banks.
Critics respond that government-linked banks can support financial inclusion, economic development and lending priorities that private institutions may not always consider commercially attractive.
Both arguments raise legitimate questions.
Private ownership can introduce capital and management expertise, but investors generally expect financial returns. Public ownership may support broader policy objectives, but it can also expose banks to political pressures and inefficient decision-making.
The effectiveness of either model depends heavily on governance, accountability and regulatory supervision.
For IDBI Bank, the practical question is whether Fairfax’s proposed ownership would improve financial performance while protecting customers and maintaining the institution’s role in the Indian economy.
That outcome cannot be determined solely by the identity of the buyer or the size of the transaction.
What Happens Next?
The future of the acquisition will depend on regulatory processes, transaction conditions and the response of relevant stakeholders.
Employee organizations and political groups may continue pressing for greater scrutiny or changes to the proposed sale.
Fairfax and the sellers will need to address concerns surrounding ownership, governance and the bank’s future direction.
Investors will also watch whether opposition affects the transaction’s expected completion or financial terms.
If the deal proceeds, attention will shift toward the new owner’s strategy for managing and developing IDBI Bank.
If it encounters significant delays or fails to close, the outcome could influence India’s future approach to privatizing financial institutions.
For now, the transaction demonstrates that major banking acquisitions cannot be evaluated purely as investment opportunities. Their success also depends on regulatory confidence, public acceptance and the ability to manage complex institutional responsibilities.
THE ABE TAKE
The proposed Fairfax acquisition of IDBI Bank is more than a $5.5 billion corporate transaction. It represents a test of how governments balance private investment with public responsibility in the banking sector.
For Fairfax, the opportunity is substantial. Acquiring control of an established Indian bank could strengthen its presence in one of the world’s largest financial markets.
For India, the transaction offers the possibility of attracting private capital and management expertise into a major banking institution.
However, employee opposition and political criticism highlight the challenges involved in transferring ownership of an organization that plays an important role in the economy.
The debate also offers a lesson for investors: financial value and political acceptance are not always the same thing. An acquisition can appear attractive on paper while facing obstacles that complicate its execution.
The central question is not simply whether a bank should be publicly or privately owned. It is whether its ownership structure encourages sound management, protects depositors and supports sustainable economic growth.
That principle should guide the assessment of major banking transactions, whether they occur in India, Canada or elsewhere.
ABE MAGAZINE
Understand More. Think Bigger.