By ABE Magazine | November 6, 2026
Canada’s federal government has unveiled proposed changes to the country’s banking regulations, seeking to make it easier for smaller financial institutions to expand and new competitors to enter one of the world’s most concentrated banking markets.
The measures, included in the 2026 federal budget, would relax ownership restrictions on growing banks, introduce a more defined approval timeline for new banking institutions and increase the amount of eligible deposits protected by federal insurance.
The proposed Canada banking reforms could mark an important shift in the country’s approach to financial regulation. While Canada has traditionally emphasized the stability of its banking system, Ottawa is increasingly focused on whether the concentration of financial services among a handful of major institutions limits competition and consumer choice.
Canada’s Big Six Dominate the Banking Industry
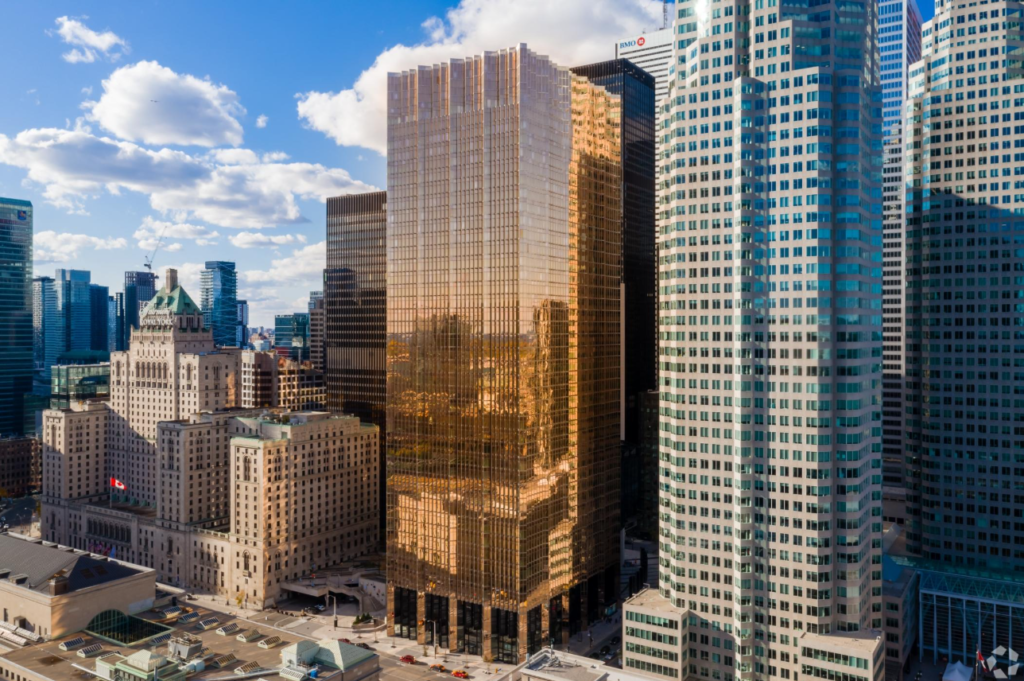
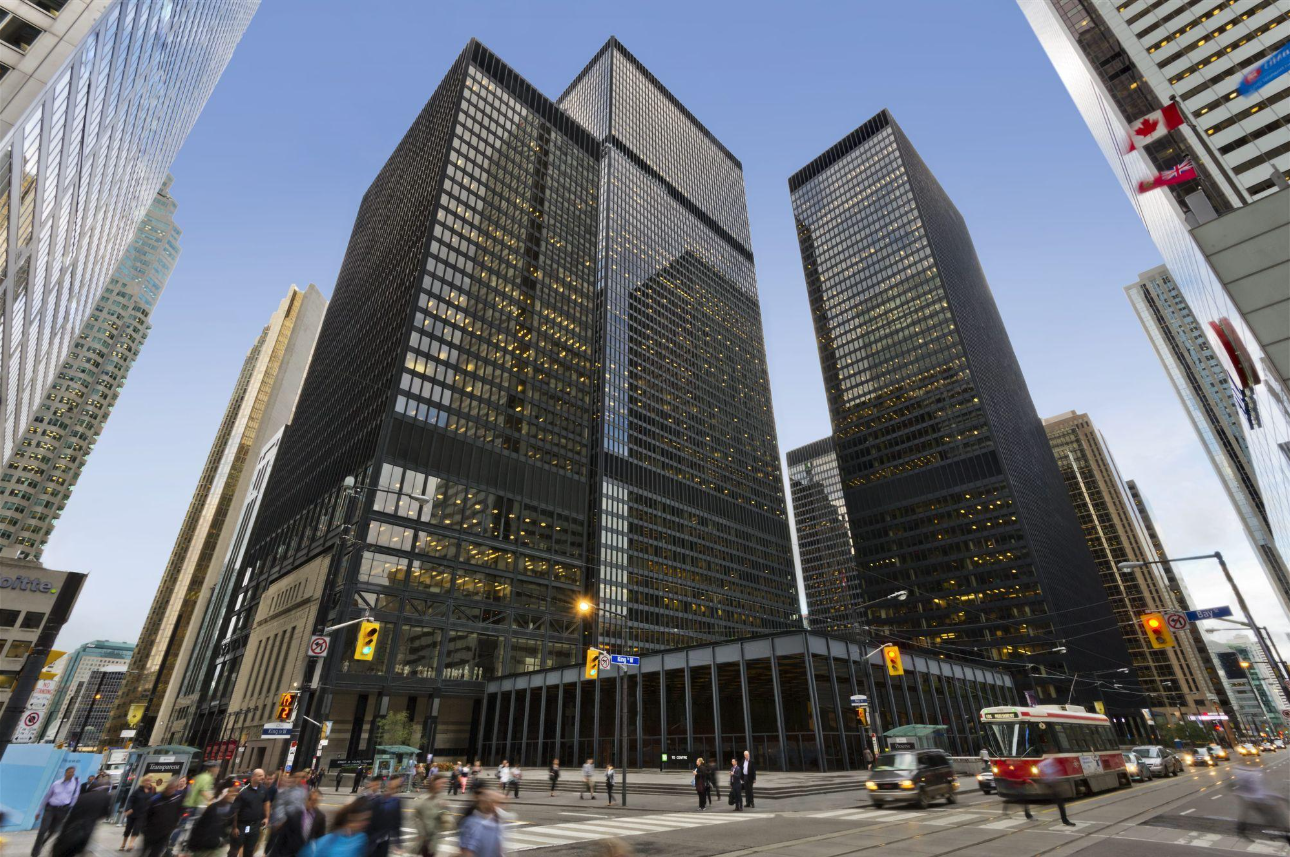
Canada’s banking sector is dominated by six major institutions: Royal Bank of Canada, Toronto-Dominion Bank, Bank of Nova Scotia, Bank of Montreal, Canadian Imperial Bank of Commerce and National Bank of Canada.
Together, these institutions account for more than 90% of the country’s banking market, according to reporting on the federal government’s proposals.
Their scale gives them substantial advantages, including established customer relationships, extensive deposit bases, recognizable brands and access to capital markets.
Large financial institutions also benefit from the ability to spread technology, compliance and operating costs across millions of customers.
However, the same concentration raises questions about the ability of smaller banks to compete effectively.
New financial institutions must invest heavily in technology, regulatory compliance, risk management and customer acquisition before they can achieve sufficient scale.
For consumers and businesses, limited competition can reduce the number of alternatives available when choosing financial products.
The federal government’s proposals seek to address some of these structural barriers without abandoning the regulatory protections that have helped maintain confidence in Canadian banking.
Ottawa Wants Smaller Banks to Grow Without Losing Ownership Control
One of the most significant proposals concerns Canada’s bank ownership rules.
Under the existing framework, a bank generally becomes subject to widely held ownership requirements once its shareholders’ equity reaches C$12 billion.
The government proposes increasing that threshold to C$25 billion.
The change would allow qualifying smaller and medium-sized banks to expand further before becoming subject to stricter ownership-dispersion requirements.
This matters because ownership restrictions can influence how banks raise capital and how their shareholders plan long-term growth.
A financial institution controlled by a founding investor or a concentrated shareholder group may face significant restructuring requirements as it becomes larger.
Raising the threshold could reduce that pressure and give growing banks more flexibility to finance expansion.
However, the proposal would not eliminate regulatory supervision or automatically allow unrestricted ownership of every financial institution.
The wider framework governing bank safety, capital adequacy and risk management would remain important.
The government’s objective is to reduce obstacles that may discourage smaller banks from challenging established competitors.
Foreign-Owned Banks Could Find It Easier to Expand
Ottawa also wants to adjust ownership rules for certain foreign bank subsidiaries operating in Canada.
Under the proposal, qualifying Canadian subsidiaries with less than C$8 billion in equity would be exempt from a public shareholding requirement, provided their foreign parent company is widely held and listed on a recognized stock exchange.
This could make Canada more attractive to international financial institutions seeking to establish or expand banking operations.
Foreign banks can introduce additional lending capacity, specialized financial products and new approaches to serving customers.
Some may focus on commercial lending, wealth management or particular customer segments rather than competing immediately across every area of retail banking.
Their participation could create additional competitive pressure on established institutions.
However, entering the Canadian market would still require significant investment and regulatory approval.
Foreign ownership flexibility alone would not guarantee that new banks could quickly attract customers or build profitable operations.
A Faster Approval Process for New Banks
Another proposed reform would establish a one-year timeline for decisions on applications to create new federally regulated banks.
The change is intended to make the authorization process more predictable.
Launching a bank is fundamentally different from creating an ordinary technology company.
A banking institution must demonstrate that it can protect depositors, maintain sufficient capital, manage financial risks and comply with extensive regulatory obligations.
Applicants must also establish governance structures, operational systems and financial controls capable of supporting a regulated institution.
These requirements are essential, but a lengthy or uncertain approval process can increase the cost of entering the market.
For entrepreneurs and investors, a more predictable timeline could improve planning and reduce uncertainty.
The proposal would not mean that every banking application must be approved within one year. Regulators would still need to determine whether applicants satisfy the applicable requirements.
Nevertheless, clearer decision timelines could make the Canadian banking industry more accessible to credible new entrants.
Deposit Insurance Could Rise to C$250,000
The federal budget also proposes a significant increase in deposit insurance protection.
The government intends to raise the Canada Deposit Insurance Corporation’s standard coverage limit from C$100,000 to C$250,000 for eligible deposits.
Deposit insurance protects qualifying deposits when a CDIC member institution fails, subject to the applicable coverage rules.
The proposed increase could be particularly important for customers considering smaller financial institutions.
Depositors may hesitate to move significant amounts of money away from established banks if they are uncertain about the safety of their savings.
A higher insurance limit could strengthen confidence in eligible deposits held at participating institutions.
The budget also proposes removing limits on eligible deposits held in certain registered and tax-free accounts.
However, these measures are proposals rather than changes that customers should assume are already in force.
Until the relevant legislation and implementation rules take effect, depositors should rely on the existing CDIC coverage framework.
What the Reforms Could Mean for Canadian Consumers
Greater banking competition could create benefits for households and businesses.
New entrants may compete through lower account fees, more attractive deposit rates, improved digital services or specialized lending products.
Smaller financial institutions may also target customers whose needs are not fully addressed by traditional banking models.
For example, a new bank might focus on small-business lending, digital financial services or customers seeking simpler financial products.
However, competition does not automatically guarantee lower prices or better services.
Banks must cover funding costs, technology investments, regulatory expenses and potential loan losses.
The success of the proposed reforms will therefore depend partly on whether smaller institutions can build sustainable businesses while offering meaningful alternatives.
Consumers could ultimately benefit from more choices, but the extent of those benefits will become clearer only after the reforms are implemented and new competitors expand.
Why Financial Stability Still Matters
Canada’s banking system has historically placed significant emphasis on prudential regulation.
The Office of the Superintendent of Financial Institutions supervises federally regulated financial institutions and assesses whether they maintain adequate capital, liquidity and risk-management practices.
The federal government proposes adding a secondary competition objective to OSFI’s mandate.
This would introduce competition more explicitly into the regulator’s considerations while preserving its responsibility for financial stability.
The balance is important.
Encouraging new banks to enter the market could improve innovation and customer choice, but excessive risk-taking could threaten depositors and undermine confidence in the financial system.
Smaller banks may face particular challenges because they often lack the diversified funding sources and operating scale available to larger competitors.
Regulators must therefore consider how competition can increase without weakening the safeguards that protect customers.
The objective should be a banking system that is both competitive and resilient.
The Bigger Opportunity for Financial Technology Companies
The proposed reforms could also influence Canada’s financial technology industry.
Fintech companies have increasingly developed digital payment services, lending platforms, personal finance applications and other financial products.
However, offering technology-based financial services is not the same as operating a federally regulated bank.
Companies seeking to accept deposits or provide banking services under a bank charter must satisfy the applicable legal and regulatory requirements.
A more predictable approval process and greater ownership flexibility could make the path toward becoming a bank more attractive for some established financial technology businesses.
It could also encourage partnerships between fintech companies and smaller regulated financial institutions.
Such partnerships may allow technology companies to provide customer-facing services while banks supply regulated financial infrastructure.
Nevertheless, obtaining a banking licence would remain a complex undertaking requiring substantial capital, experienced management and strong compliance systems.
The proposed reforms could lower certain barriers, but they would not eliminate the financial and operational responsibilities associated with banking.
Can the Reforms Really Challenge the Big Six?
The central question is whether these changes will produce meaningful competition.
Canada’s major banks possess significant advantages that cannot be removed through regulatory amendments alone.
Their established brands, customer relationships, capital resources and technology investments create formidable barriers for new entrants.
Smaller institutions must also compete for deposits and qualified employees while meeting demanding regulatory standards.
However, the government’s proposals could gradually change the competitive environment.
Allowing banks to grow further before triggering ownership restrictions may encourage additional investment in mid-sized institutions.
A clearer authorization process could attract entrepreneurs and investors interested in establishing new banks.
Higher deposit insurance coverage could also make customers more comfortable considering alternatives to established financial institutions.
The effects are likely to develop over several years rather than immediately.
Ultimately, the success of the reforms will depend on whether they encourage viable new institutions, expand consumer choice and maintain financial stability.
THE ABE TAKE
Canada’s proposed banking reforms address an important weakness in an otherwise highly developed financial system: a market can be financially stable while still offering limited competition.
The country’s largest banks have built strong institutions with extensive domestic and international operations. Their scale provides financial resilience, but it also makes it difficult for smaller competitors to establish themselves.
Raising the ownership threshold from C$12 billion to C$25 billion could help growing banks attract investment without facing premature restructuring requirements.
A more predictable approval process could also make banking a more realistic ambition for well-capitalized financial entrepreneurs.
However, the most important measure of success will not be the number of new banking licences issued.
It will be whether Canadians gain access to better financial products, competitive pricing and institutions capable of serving customers that existing banks may overlook.
The government must also ensure that increased competition does not weaken the financial protections that support confidence in Canada’s banking system.
The opportunity is not simply to create more banks. It is to create a financial system in which new institutions can grow, established banks must compete more actively, and consumers benefit without sacrificing stability.
If implemented effectively, the reforms could represent an important step toward a more open and competitive Canadian banking industry.
ABE MAGAZINE
Understand More. Think Bigger.