









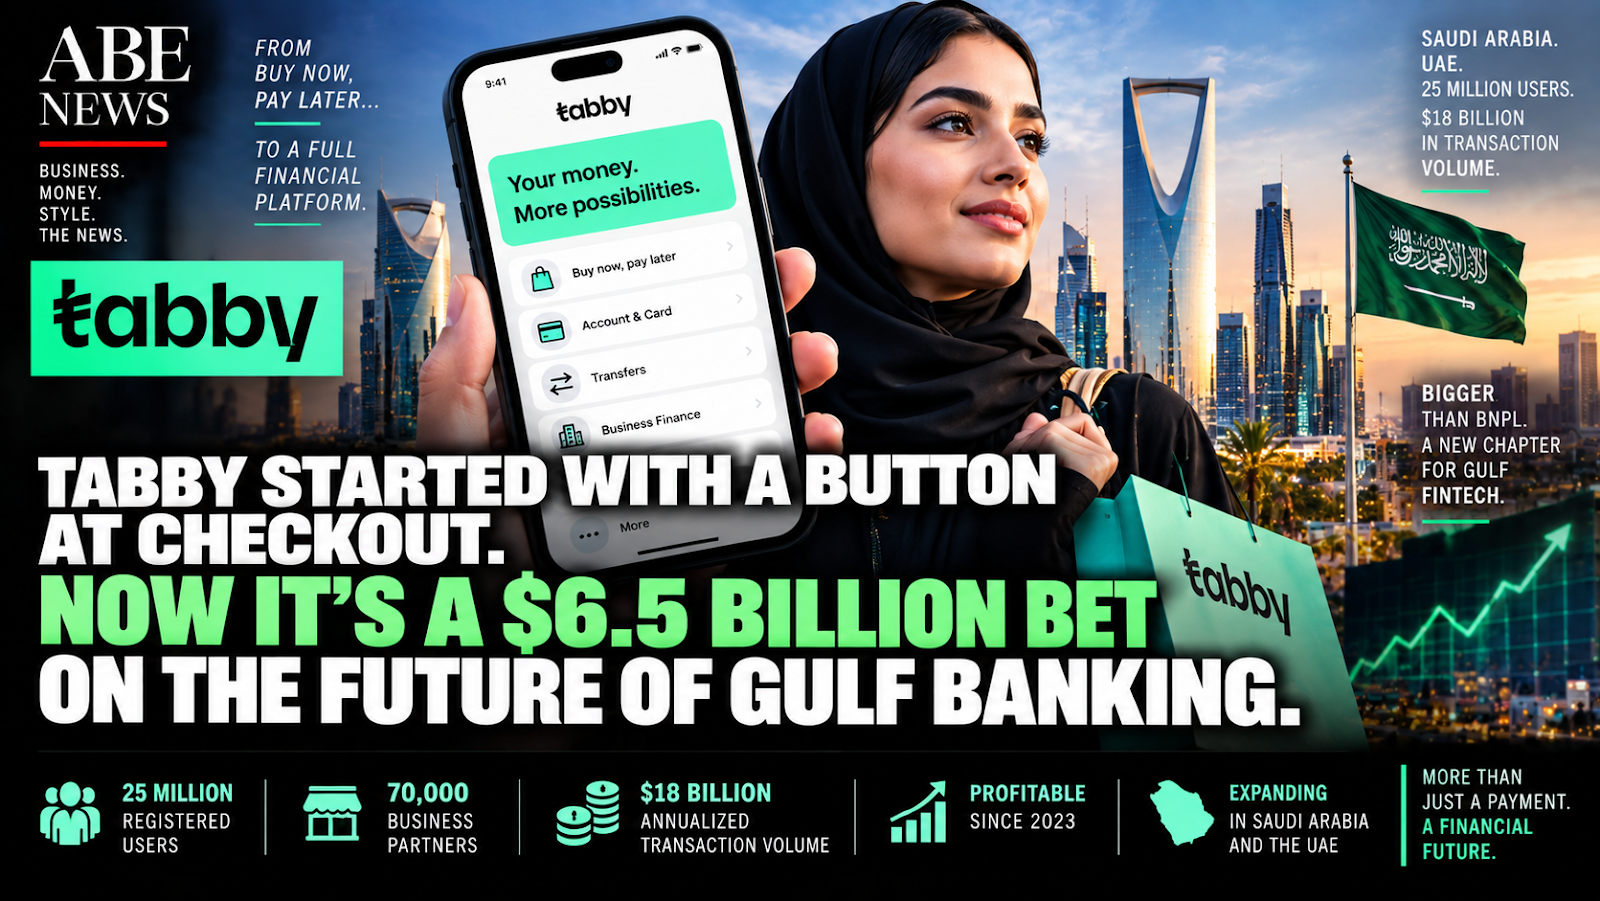
ABE NEWS | September 14, 2026
In 2019, Tabby’s proposition was remarkably simple.
A customer wanted to buy something online but didn’t necessarily want to pay the entire amount immediately. Tabby placed itself at checkout and allowed that purchase to be divided into instalments.
No bank branch. No traditional credit-card application. No complicated financial relationship.
Just a button.
Seven years later, that button has helped create one of the Middle East’s most valuable financial-technology companies.
Saudi Arabia-headquartered Tabby has raised $233 million in a Series F funding round that values the company at $6.5 billion, according to an announcement Monday. Blue Pool Capital led the round, with participation from HSG, Wellington Management and Arbor Ventures. The financing included both new and existing shares and will also provide liquidity to employees.
The valuation alone would make the deal significant.
But it isn’t the most interesting part of the story.
Tabby is no longer content with being the company consumers encounter when they want to split a purchase into four payments.
It wants to become part of what happens before the purchase, after the purchase and everywhere else people manage their money.
In Saudi Arabia, new licences are allowing it to offer larger and longer-term consumer financing and working capital to businesses. In the United Arab Emirates, it has moved into spending accounts, cards and transfers through Tabby Cash. Its acquisition of digital-wallet company Tweeq gives it additional financial infrastructure in Saudi Arabia.
Tabby began by challenging one small piece of traditional finance.
Now it is beginning to challenge something considerably larger.
The relationship between Gulf consumers and their banks.
THE $6.5 BILLION NUMBER DIDN’T COME FROM NOWHERE
Tabby’s valuation has risen remarkably quickly.
In February 2025, a $160 million Series E valued the company at $3.3 billion.
By October 2025, a secondary share transaction implied a valuation of $4.5 billion.
Now, less than a year later, investors are valuing the business at $6.5 billion.
That means Tabby’s private-market valuation has nearly doubled in roughly nineteen months.
Investors aren’t simply paying for an idea.
Tabby says it now has 25 million registered users, works with approximately 70,000 businesses and processes more than $18 billion in annualized transaction volume. Its merchant network includes companies such as Amazon and Shein.
Perhaps more important in today’s venture-capital environment, Tabby says it is profitable.
CEO and co-founder Hosam Arab told Reuters that the company is profitable and sufficiently well capitalized that it does not need to rush into an initial public offering simply to obtain more money.
That’s an important distinction.
The technology boom of the previous decade created plenty of companies that became extremely valuable before demonstrating that they could become profitable.
Tabby is trying to tell investors a different story:
We are still growing rapidly — but growth does not require us to burn unlimited amounts of money.
BUY NOW, PAY LATER WAS THE DOOR
Tabby’s original product belongs to a category known as buy now, pay later, or BNPL.
The concept became one of fintech’s biggest global trends.
Instead of paying $400 immediately for a purchase, a customer might divide the cost into several payments. The merchant receives the sale, the consumer gains flexibility and the BNPL provider sits between them.
For merchants, there is an obvious attraction.
Making a purchase easier to afford can make a customer more likely to complete it.
A shopper who hesitates at a $500 price tag might feel differently when the purchase can be divided into smaller payments.
That can improve conversion rates and potentially increase how much consumers spend.
The merchant therefore has an economic reason to pay the financial provider facilitating the transaction.
But BNPL also provides the fintech with something that may become even more valuable over time:
a relationship with the customer.
Every transaction creates information.
What does the person buy?
How frequently?
How much?
Do they repay on time?
How do they behave across different merchants?
As the customer repeatedly uses the platform, Tabby becomes something more than a checkout option.
It becomes part of that person’s financial life.
And once you have millions of customers already trusting you with payments, the obvious strategic question becomes:
What else can you offer them?
THAT QUESTION IS NOW DEFINING TABBY’S NEXT CHAPTER
The company’s answer appears increasingly ambitious.
Tabby has spent the past year obtaining licences that allow it to move deeper into financial services.
In Saudi Arabia, it has secured consumer and SME finance licences from the Saudi Central Bank, enabling it to offer larger and longer-term financing to consumers as well as working capital to businesses.
That moves Tabby beyond helping somebody divide the cost of shoes or electronics.
A business that already processes payments for tens of thousands of merchants can potentially use that relationship to provide financing when those merchants need capital.
The logic is powerful.
Suppose Tabby already knows how much a merchant sells through its platform.
It can observe transaction patterns.
It can see growth.
It can potentially understand parts of the business’s cash flow.
That information could help it make lending decisions differently from a traditional financial institution starting with little knowledge of the merchant.
Payments can therefore become the foundation for credit.
Credit can become the foundation for a much broader financial relationship.
This is a pattern we have seen elsewhere in fintech.
The first product gets the customer through the door.
The second, third and fourth products determine how valuable that customer ultimately becomes.
TABBY CASH MAY BE THE MORE IMPORTANT PRODUCT TO WATCH
The company’s UAE expansion makes that ambition even clearer.
Tabby has received a Stored Value Facilities licence from the Central Bank of the UAE and launched Tabby Cash, which pushes the company toward everyday money management.
The product includes a spending account and card, cashback, local money transfers and international-transfer capabilities.
Think about what that means strategically.
BNPL is something consumers may use occasionally.
A spending account can be used every day.
A customer might use BNPL when buying a television.
But a card can potentially be used for groceries, transportation, restaurants, subscriptions and dozens of ordinary purchases.
That difference matters enormously.
Financial companies become powerful when they move from being a service customers sometimes need to infrastructure customers regularly use.
Tabby Cash is an attempt to make that transition.
If successful, Tabby stops being something sitting beside Visa, Mastercard and the banks at checkout.
It starts competing for the relationship those institutions have with the customer.
THE TWEEQ ACQUISITION FILLS IN ANOTHER PIECE
Tabby has also been building rather than merely launching products.
In 2024, it acquired Saudi digital-wallet company Tweeq.
Tweeq already held a licence from the Saudi Central Bank, giving Tabby capabilities across areas such as accounts, cards and transfers.
This is a classic way for a rapidly expanding financial company to accelerate.
Building regulated financial infrastructure from scratch can take time.
Acquiring a company that already possesses technology, expertise and regulatory permissions can move much faster.
The acquisition also reveals where Tabby sees itself going.
A pure BNPL company doesn’t necessarily need an entire digital-wallet platform.
A company trying to become a broader financial institution does.
Put the pieces together:
Instalments.
Consumer finance.
SME working capital.
Accounts.
Cards.
Transfers.
Suddenly, the company begins to look much less like a checkout feature.
And much more like a bank without the traditional bank history.
SAUDI ARABIA IS THE CENTRE OF THE STRATEGY
Tabby was founded in 2019 and moved its headquarters to Riyadh in 2023.
That decision makes considerably more sense when viewed against what is happening across Saudi Arabia.
The kingdom is attempting one of the world’s most ambitious economic transformations.
Under Vision 2030, Saudi Arabia has been trying to diversify its economy beyond oil by developing technology, tourism, entertainment, logistics, financial services and other industries.
A young population, widespread smartphone adoption and government support for digital payments create fertile conditions for fintech companies.
Saudi Arabia also represents a large consumer market compared with many of its Gulf neighbours.
For Tabby, this means it can potentially become a major financial platform while the country’s financial system itself is undergoing rapid change.
That is a very different opportunity from entering a mature market where consumer financial habits have remained unchanged for decades.
Tabby isn’t simply trying to steal customers from traditional financial institutions.
It is growing alongside a market whose consumers are becoming increasingly comfortable with digital alternatives.
THE UAE OFFERS A DIFFERENT ADVANTAGE
If Saudi Arabia offers scale, the United Arab Emirates offers another attractive combination.
High consumer spending.
A large expatriate population.
Sophisticated financial infrastructure.
Strong e-commerce penetration.
And a government that has aggressively encouraged fintech development.
Together, Saudi Arabia and the UAE give Tabby two substantial Gulf markets from which to build.
And Hosam Arab says that is exactly where the new capital is going.
The proceeds, he told Reuters, are primarily intended to allow Tabby to go deeper in its two core markets rather than fund some uncontrolled international expansion.
That may be one of the smarter elements of the strategy.
Startups often treat geographic expansion as proof of success.
More countries.
More flags on the website.
More announcements.
But financial services are intensely local.
Regulations differ.
Credit behaviour differs.
Consumer habits differ.
Banking systems differ.
Payment infrastructure differs.
A company can spread itself across twenty countries and still have less strategic depth than one dominating two enormous markets.
Tabby appears, at least for now, to prefer depth.
AND THEN THERE’S THE PROFIT QUESTION
Fintech growth can be expensive.
Companies spend heavily acquiring customers.
They subsidize transactions.
They offer rewards.
They invest in compliance and technology.
And lending introduces an additional cost that pure software businesses don’t face:
some customers won’t repay.
That makes Tabby’s profitability particularly important.
According to reporting on its publicly available Saudi subsidiary accounts, the operation generated approximately $378 million in revenue and $55 million in net profit in 2025, although profit growth has come under pressure this year as the business spends more and provisions for greater credit losses.
That last part should not be ignored.
When a financial company expands lending, growth and risk frequently increase together.
More loans create more interest and fee opportunities.
They also create more chances for customers to default.
That is one of the reasons becoming a broader financial institution is harder than building a successful payments application.
A software bug can damage a fintech.
A bad credit model can destroy one.
BNPL HAS ALWAYS HAD AN UNCOMFORTABLE SIDE
The appeal of buy now, pay later is obvious.
It gives consumers flexibility.
But the same feature creates the industry’s central criticism.
Making purchases feel cheaper can encourage people to spend money they do not really have.
Four payments of $100 can psychologically feel easier than one payment of $400.
Economically, the customer still owes $400.
If a consumer simultaneously uses several instalment services across different purchases, those seemingly manageable payments can accumulate.
That means the success of companies like Tabby ultimately depends partly on whether they can grow credit responsibly.
The larger Tabby becomes, the more important that responsibility becomes.
At 25 million registered users, this is no longer a tiny startup experimenting with a payment feature.
It is becoming significant financial infrastructure.
And financial infrastructure eventually attracts scrutiny.
REGULATION MAY ACTUALLY BECOME AN ADVANTAGE
Startups often treat regulation as an obstacle.
For Tabby, it may eventually become part of the moat.
Financial licences are difficult to obtain for a reason.
Regulators need confidence that companies handling customer money, issuing credit and operating payment systems have appropriate controls.
Once a fintech obtains those licences and builds the compliance infrastructure required to maintain them, the barrier for a new competitor becomes higher.
Anyone can build a beautiful finance app.
Not everyone can legally hold customer funds, issue regulated financing and operate payments infrastructure at enormous scale.
Tabby’s licences in Saudi Arabia and the UAE therefore do more than unlock new products.
They potentially make the company harder to replicate.
That matters because the biggest threat to a successful fintech isn’t necessarily another startup.
It can be an incumbent bank that decides to copy the product.
THE BANKS ARE NOT GOING TO DISAPPEAR
Fintech history is full of predictions that technology companies would destroy traditional banks.
That has rarely happened.
Banks possess enormous advantages.
Deposits.
Capital.
Regulatory relationships.
Established customer bases.
Corporate clients.
Credit expertise.
Payment infrastructure.
And, perhaps most importantly, trust built over decades.
Tabby therefore doesn’t need to eliminate banks to become extremely valuable.
It needs to own enough of the customer relationship that banks become less central.
Imagine a consumer who receives money through one platform, pays with its card, finances larger purchases through it, transfers money through it and eventually uses it for savings or other financial products.
The traditional bank account may still exist.
But it has moved into the background.
That is the strategic prize many fintech companies are chasing.
Not necessarily becoming a bank in the traditional sense.
Becoming the financial interface through which the customer experiences money.
THE MERCHANT RELATIONSHIP COULD BE JUST AS IMPORTANT
The consumer side gets most of the attention.
But Tabby’s relationship with approximately 70,000 businesses may eventually become one of its strongest assets.
Those merchants already use Tabby to increase payment flexibility for customers.
Now Tabby can potentially sell them more.
Working capital.
Payment processing.
Analytics.
Business financial products.
Perhaps eventually payroll, expense management or other services.
The exact product mix will evolve.
But the strategic principle is straightforward.
Acquiring a business customer is expensive.
Once you have one, selling that same customer another useful product can be considerably cheaper.
That is why fintech companies frequently expand horizontally.
The first product establishes trust.
Additional products increase revenue per customer.
Eventually, the company becomes harder to replace because removing it means replacing several financial services at once.
TABBY HAS SOMETHING ELSE INVESTORS LIKE: DATA
Twenty-five million registered users and billions of dollars flowing through a platform generate enormous quantities of information.
That does not mean Tabby can simply use customer data however it wants. Financial privacy and regulation place important restrictions around that information.
But within those boundaries, transaction and repayment histories can potentially improve underwriting.
Traditional lending has historically relied heavily on credit histories, income verification and other formal financial information.
Digital financial platforms can sometimes observe different signals.
How frequently does a customer transact?
How reliably do they repay?
How does behaviour change over time?
For merchants, what are sales patterns?
Are revenues growing?
Are transactions seasonal?
Better information can theoretically lead to better credit decisions.
And better credit decisions are incredibly valuable.
A lender that approves too few borrowers leaves revenue on the table.
A lender that approves too many risky borrowers loses money.
The entire business sits between those two mistakes.
THE IPO CAN WAIT
A company valued at $6.5 billion naturally attracts one question:
When will it go public?
For now, Hosam Arab isn’t committing.
He told Reuters that because Tabby is profitable and well capitalized, it does not need to force the timing. If the company eventually lists, he said it will choose the market that best fits Tabby, its shareholders and its long-term growth.
That is an enviable position.
Private companies often eventually face pressure to go public because employees and early investors want liquidity or because the business needs additional capital.
Tabby is already addressing some employee liquidity through secondary transactions. It says more than $100 million in employee share sales has been facilitated through tender offers since 2023.
That can reduce some of the urgency.
The company has also spent years positioning itself closer to Saudi Arabia’s capital markets, and speculation around a potential Tadawul listing has persisted.
An eventual Saudi listing would carry significance beyond Tabby.
It could become another demonstration that the Gulf can produce technology companies large enough to mature through regional capital markets rather than automatically looking to New York or London.
THIS IS ALSO A STORY ABOUT WHERE STARTUPS ARE BEING BUILT
For years, the geography of global technology seemed predictable.
Silicon Valley dominated.
Then China created enormous technology companies.
Europe produced its own champions.
India’s startup ecosystem exploded.
Now the Gulf increasingly wants a place on that map.
Governments and sovereign wealth funds across the region are deploying enormous amounts of capital into technology. International venture firms are increasing their presence. Founders are relocating businesses. Saudi Arabia and the UAE are competing to become regional centres for fintech, AI and other emerging industries.
Tabby’s $6.5 billion valuation doesn’t prove that the Gulf has become the next Silicon Valley.
It does demonstrate something more meaningful:
A technology company built primarily around Middle Eastern consumers can now reach multi-billion-dollar scale without treating the region merely as a stepping stone toward America or Europe.
That changes the entrepreneurial equation.
A founder in the Gulf can increasingly build for the Gulf and still create an enormous company.
THE HARDEST PART STARTS NOW
Going from zero to $6.5 billion is difficult.
Going from a successful fintech product to a durable financial institution may be harder.
Tabby now has to prove that its brand can stretch.
Customers who trust it to split a purchase into four payments must trust it to hold money.
Merchants using it at checkout must trust it for working capital.
Regulators must trust its controls.
Investors must trust its credit discipline.
And the company must continue growing without allowing losses from lending to overwhelm the economics that made the business attractive in the first place.
This is the tension at the heart of Tabby’s next chapter.
The products that could make it much bigger are also products that introduce much greater complexity.
Payments are difficult.
Banking is harder.
Credit can be unforgiving.
🔴 THE ABE NEWS TAKE
The easiest way to describe today’s news is:
Tabby raised $233 million at a $6.5 billion valuation.
But that misses what is actually happening.
The more important story is that Tabby is attempting one of fintech’s most difficult transformations.
It is trying to turn distribution into a financial institution.
The company first built distribution by appearing exactly where consumers were already spending money: checkout.
That gave it merchants.
Those merchants brought consumers.
Those consumers generated transactions.
Those transactions generated data.
The data helped deepen the relationship.
And now Tabby is attempting to use that foundation to move into accounts, cards, transfers, larger consumer financing and business credit.
The progression looks logical when viewed from the outside.
Executing it is anything but simple.
The next phase will require Tabby to prove that the financial discipline that helped it become profitable can survive as lending expands. It will have to manage credit losses, satisfy regulators and compete against banks with much deeper balance sheets.
But there is a reason investors are willing to value the company at $6.5 billion.
If Tabby succeeds, the prize is considerably larger than buy now, pay later.
A checkout button is useful.
A financial relationship can last decades.
And perhaps the most important lesson from Tabby’s rise is one we’ve seen repeatedly in great technology businesses:
The first product doesn’t always reveal the size of the company being built.
Amazon began with books.
Uber began with black cars.
Shopify began by trying to sell snowboards online.
Tabby began with a way to divide a purchase into several payments.
Seven years later, the company isn’t merely asking Gulf consumers to use Tabby when they shop.
It increasingly wants them to use Tabby when they manage money itself.
If it can make that transition, $6.5 billion may eventually be remembered not as the culmination of Tabby’s growth —
but as the valuation attached to the moment it stopped looking like a BNPL company and started looking like something much closer to a bank.
ABE NEWS
Business. Money. Style. The News.
Understand More. Think Bigger.



