By ABE Magazine | November 6, 2026
Africa’s corporate debt markets remain too small to support the continent’s growing investment needs, according to a new report from the Organisation for Economic Co-operation and Development (OECD). The findings reveal a financial system in which companies depend heavily on bank-led borrowing, domestic bond markets remain underdeveloped, and access to long-term financing is concentrated in only a handful of countries.
The OECD’s Africa Capital Markets Report 2026, published on November 6, estimates that outstanding market-based corporate debt across all 54 African countries reached just US$211 billion at the end of 2025. That represented only 0.3% of global corporate debt, despite Africa accounting for approximately 2.7% of the world’s economic output.
The findings highlight a structural challenge for African economies. Businesses need financing to build factories, expand operations, develop infrastructure and create employment. Yet the financial markets that could provide that capital remain limited in scale, leaving many companies dependent on traditional bank loans or international lenders.
A $211 Billion Market for an Entire Continent
The OECD’s findings cover three forms of market-based corporate borrowing: corporate bonds, syndicated loans and private credit.
Together, these financing channels accounted for US$211 billion in outstanding corporate debt at the end of 2025. The figure does not represent every business loan across Africa. Instead, it measures specific market-based financing instruments tracked in the report.
The distinction matters because many African companies, particularly smaller businesses, continue to rely on direct loans from commercial banks. Those loans remain an important source of funding but do not provide the same range of financing options available to companies in more developed capital markets.
The OECD found that syndicated loans accounted for approximately 81% of outstanding market-based corporate debt. These are loans arranged by groups of financial institutions, typically for borrowers requiring substantial amounts of capital.
Corporate bonds, by comparison, accounted for only US$35 billion.
In more developed financial systems, companies can raise money by issuing bonds directly to investors, including pension funds, insurance companies and asset managers. This allows businesses to diversify their funding sources and sometimes secure financing for longer periods.
Across much of Africa, that alternative remains limited.
Africa’s Corporate Bond Market Has Shrunk
One of the report’s most striking findings concerns the decline of corporate bond financing.
The OECD estimates that Africa’s corporate bond market was 44% smaller in inflation-adjusted terms than its 2015 peak. Much of that contraction was associated with reduced activity in South Africa, the continent’s largest corporate debt market.
Only 20 or fewer corporate bonds were issued across Africa in 2025, according to the report. Seventeen of those issues came from financial companies, leaving very limited issuance by businesses operating outside the financial sector.
This concentration raises concerns about the ability of manufacturers, logistics companies, agricultural businesses and other enterprises to raise long-term capital.
Corporate bonds can be especially useful for financing projects that require significant upfront investment but generate revenue over many years.
A manufacturing company, for example, may need substantial capital to construct a production facility. If it relies entirely on short-term borrowing, it could face refinancing difficulties before the facility generates sufficient revenue.
Longer-term bonds can help match financing obligations with the expected life of an investment.
However, establishing a functioning bond market requires more than companies willing to borrow. Investors must trust the legal system, financial disclosures, currency environment and institutions responsible for protecting their interests.
Six Countries Dominate African Corporate Borrowing
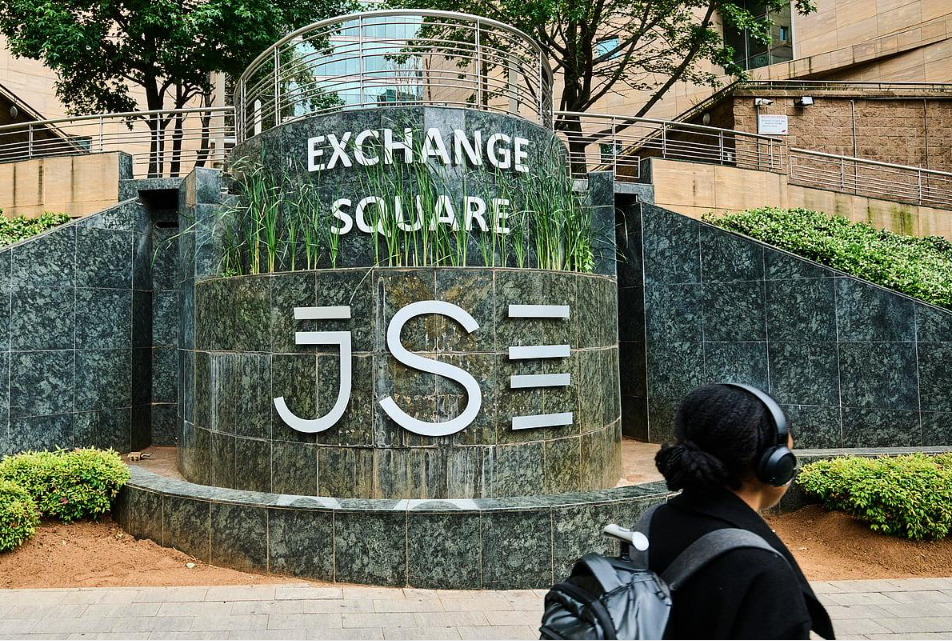
The report also reveals significant differences between African financial markets.
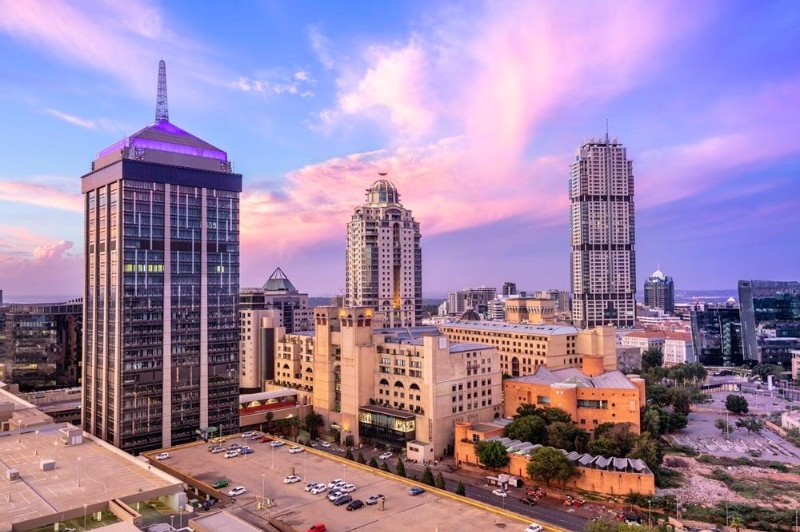
Six countries — South Africa, Egypt, Mauritius, Morocco, Mozambique and Nigeria — accounted for approximately 80% of outstanding corporate debt at the end of 2025.
South Africa alone represented about 30%, with approximately US$63 billion outstanding.
These figures demonstrate how unevenly financial-market development is distributed across the continent.
South Africa benefits from established financial institutions, institutional investors and relatively developed capital-market infrastructure. Other countries have smaller investor bases, fewer large corporate issuers and more limited secondary markets for trading securities.
For businesses operating outside the major financial centres, raising capital can therefore be substantially more difficult.
A company may have a commercially viable project but lack access to investors willing to provide the financing required.
The consequences extend beyond individual businesses. Limited access to capital can restrict industrial expansion, infrastructure development and economic diversification.
It can also reinforce the advantages enjoyed by large, established companies that already have relationships with major banks and international lenders.
Foreign-Currency Borrowing Creates Another Risk
A particularly important concern identified by the OECD is Africa’s reliance on foreign-currency borrowing.
Only 17% of corporate debt issued in 2025 was denominated in local currencies. This means most new market-based borrowing was arranged in foreign currencies, including international currencies such as the US dollar and euro.
Foreign-currency financing can help companies access larger pools of international capital. However, it also introduces financial risk when a company’s revenues are primarily earned in its domestic currency.
Consider a business that borrows US$10 million while generating most of its income in a local African currency.
If that currency weakens against the US dollar, the amount required to repay the loan increases when measured in local currency, even though the original dollar-denominated debt remains unchanged.
The company may then need to allocate more of its revenue toward debt repayments, leaving less money available for wages, investment and business expansion.
This problem is known as a currency mismatch.
Businesses that earn substantial foreign-currency revenue, such as some exporters, may have a natural source of protection. Companies serving primarily domestic customers often face greater exposure.
The OECD warns that developing deeper local-currency debt markets would help reduce these vulnerabilities and strengthen financial resilience.
Why African Banks Cannot Finance Everything
Commercial banks play a central role in African economies, providing credit to businesses and households while supporting payments and other financial services.
However, relying too heavily on banks creates limitations.
Banks must manage liquidity, capital requirements and the risks associated with their lending portfolios. They cannot always provide the amount or duration of financing required for large industrial and infrastructure projects.
Corporate bond markets can complement bank lending by connecting companies with institutional investors seeking long-term returns.
Pension funds, for example, collect contributions that may be invested over many years. Properly regulated corporate bonds can provide one way to invest part of those funds in productive domestic businesses.
Insurance companies also manage long-term financial obligations and can participate in debt markets where suitable investment opportunities exist.
According to the OECD, domestic insurance companies accounted for approximately 19% of African corporate bond holdings in 2025.
Expanding these investment channels could reduce excessive dependence on banks while giving companies more financing choices.
However, stronger bond markets would not eliminate the need for commercial banking. Banks would remain important lenders, financial intermediaries and participants in capital-market transactions.
Smaller Businesses Face the Greatest Financing Challenges
The OECD found that access to market-based corporate debt remains concentrated among larger businesses.
Median transaction sizes for corporate bonds and syndicated loans in Africa exceeded those in the broader emerging-market group, suggesting that financing is disproportionately available to major companies.
This creates difficulties for small and medium-sized enterprises.
Smaller companies often lack the financial reporting systems, credit ratings, collateral or scale required to attract institutional investors.
Issuing a bond also involves legal, regulatory and administrative costs that may be difficult to justify for a relatively small financing requirement.
As a result, many businesses remain dependent on traditional bank lending, retained earnings or investment from their owners.
That dependence can restrict expansion when banks are unwilling to provide sufficient credit or when borrowing costs become too high.
The problem is particularly important for African economies seeking to develop manufacturing, agriculture, technology and domestic supply chains.
A business may identify strong customer demand but still struggle to purchase equipment, expand facilities or hire additional workers.
Improving access to finance therefore requires more than increasing the total amount of money available. It also requires financial products and institutions capable of serving companies at different stages of development.
Private Credit Is Growing, but Remains Small
Private credit has emerged as another potential source of financing.
Unlike publicly traded corporate bonds, private credit generally involves lending arrangements negotiated outside public securities markets, often through specialized investment funds.
The OECD reports that assets under management in Africa-focused private credit funds increased from approximately US$2.2 billion in 2020 to US$5.5 billion in 2025.
This growth suggests increasing investor interest in alternative financing opportunities.
However, the market remains small compared with Africa’s overall investment requirements.
The report also notes that a meaningful portion of private credit capital has not yet been deployed into investments.
This indicates that attracting investment commitments does not automatically translate into financing for businesses.
Investors must still identify suitable borrowers, assess risks and negotiate transactions that meet their return requirements.
Private credit could become an important complement to banks and bond markets, but it is unlikely to solve the continent’s financing challenges on its own.
Africa’s Stock Markets Are Growing Faster Than Its Debt Markets
The report presents a contrasting picture of African equity markets.
Stock-market capitalization across the continent increased approximately 49% in 2025, significantly outperforming the broader emerging-market benchmark.
However, that growth was concentrated in relatively few markets.
South Africa, Egypt, Nigeria and Morocco accounted for approximately 88% of African listed-company market value.
Much of the increase also came from rising share prices rather than a large number of new businesses entering public markets.
This distinction is important because a rising stock market does not necessarily mean that companies are raising substantial amounts of new capital.
When existing shares increase in value, shareholders may become wealthier, but businesses do not automatically receive additional funding.
New share offerings, by contrast, can provide companies with capital to finance expansion.
The OECD’s findings suggest that Africa’s financial-market development must be assessed through more than stock-market performance alone.
The ability of businesses to raise new debt and equity financing is equally important.
What Governments Need to Change
The OECD argues that the most important obstacles to corporate bond-market development are often economic and institutional rather than purely technical.
Countries need credible financial regulation, stable economic conditions and legal systems capable of protecting investors and enforcing contracts.
Currency stability also matters because investors are less willing to provide long-term financing when exchange-rate movements could significantly reduce their returns.
Another important requirement is the development of government bond markets.
When governments issue bonds across different maturities, those securities can help establish benchmark interest rates that investors use to price corporate debt.
Pension funds and insurance companies can then provide a domestic investor base capable of supporting longer-term corporate financing.
The OECD recommends coordinated reforms that extend beyond securities regulators to include broader economic policy, institutional quality and financial-market infrastructure.
This approach recognizes that a corporate bond exchange cannot succeed simply because a government creates a trading platform.
Investors must first have confidence in the wider financial environment.
Why the Findings Matter for Africa’s Economic Future
Africa faces substantial financing requirements in infrastructure, education, energy and industrial development.
The OECD cites estimates indicating that the continent needs more than US$400 billion annually to achieve strong progress across selected development goals involving education, energy, productivity and infrastructure.
These investment needs come at a time when international development assistance has become less reliable.
The report notes that official development assistance from OECD donor countries to sub-Saharan Africa fell by more than one-quarter in a single year.
This strengthens the argument for mobilizing more domestic savings and private investment.
Developing capital markets could help channel money held by pension funds, insurers and other investors toward productive businesses.
However, the objective should not be to encourage companies to borrow without restraint.
Excessive debt can create financial instability, particularly when borrowers face high interest rates or volatile revenues.
The more important goal is to build financial systems that allocate capital responsibly, support productive investment and remain resilient during economic downturns.
THE ABE TAKE
Africa’s US$211 billion corporate debt market reveals a fundamental weakness in the continent’s financial architecture.
The challenge is not simply that African businesses need more money. It is that the institutions and markets capable of providing long-term financing remain too limited, concentrated and dependent on foreign currencies.
A continent representing 2.7% of global economic output but only 0.3% of global corporate debt demonstrates a substantial imbalance in access to market-based capital.
For banks, the findings highlight the importance of developing financial systems in which traditional lending operates alongside corporate bonds, pension funds, insurance companies and responsible private credit.
For governments, the priority should be building investor confidence through stronger institutions, predictable regulation and greater economic stability.
For businesses, deeper domestic capital markets could create opportunities to finance expansion without relying entirely on short-term bank credit or foreign-currency borrowing.
However, capital-market development cannot be achieved through financial products alone. Investors must trust the institutions, legal systems and economic conditions supporting those products.
Africa’s long-term economic growth will depend not only on attracting foreign investment, but also on building financial institutions capable of transforming domestic savings into productive capital.
The continent has businesses seeking to expand and investors searching for opportunities. The challenge is creating financial markets strong enough to connect them.
ABE MAGAZINE
Understand More. Think Bigger.