By ABE Magazine | November 6, 2026
Investors affected by the 2023 collapse of Silicon Valley Bank have reached a US$224.5 million settlement with accounting firm KPMG LLP, marking a significant development in the legal aftermath of one of the largest bank failures in American history.
The agreement was announced on Friday, November 6, by Norway’s sovereign wealth fund, which participated in the investor class-action lawsuit. KPMG, which served as the bank’s external auditor, said the settlement was a business decision and did not constitute an admission of wrongdoing.
The Silicon Valley Bank KPMG settlement brings renewed attention to the responsibilities of auditors, the importance of financial transparency and the risks investors face when major financial institutions fail.
Although the agreement represents a step toward recovering investor losses, litigation against other defendants continues.
A $224.5 Million Settlement After a Historic Bank Failure
The settlement follows legal proceedings brought by investors after Silicon Valley Bank collapsed in March 2023.
The failure triggered widespread concern across the banking industry, with investors questioning whether other financial institutions faced similar vulnerabilities.
According to Reuters, the US$224.5 million agreement was reached with KPMG, the bank’s external auditor.
Norway’s sovereign wealth fund welcomed the settlement as an important development in recovering losses suffered by investors.
However, the agreement does not establish that KPMG committed wrongdoing. The accounting firm has maintained that it stands behind the quality of its audit work.
The distinction matters because settlements can resolve financial disputes without a court determining liability.
The investor lawsuit also remains active against other defendants, meaning the broader legal consequences of Silicon Valley Bank’s collapse have not been fully resolved.
Why Silicon Valley Bank Collapsed
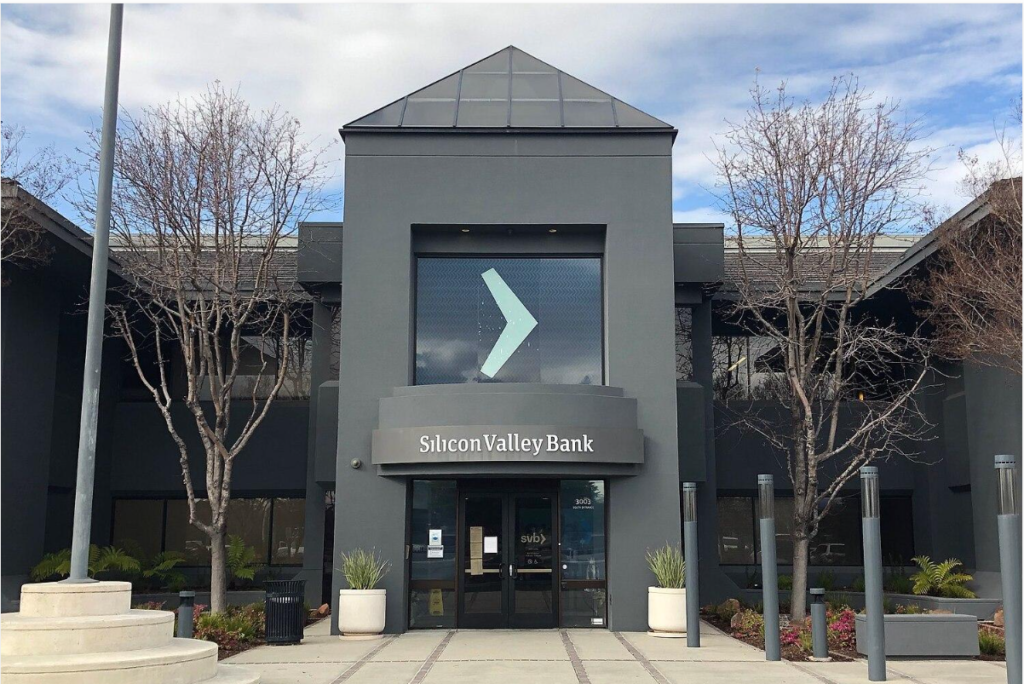
Silicon Valley Bank was closely associated with technology companies, venture capital firms and startups.
Its business model created a substantial concentration of customers operating within the technology and innovation economy.
During a period of rapid deposit growth, the bank invested significant funds in longer-term securities, including government-backed debt instruments.
As interest rates increased, the market value of many existing fixed-income investments declined.
Higher interest rates generally reduce the value of older bonds paying lower yields because newly issued securities become more attractive to investors.
Silicon Valley Bank faced an additional challenge when customers began withdrawing deposits.
Many of its clients were businesses with substantial cash balances, making the bank particularly exposed to large and rapid withdrawals.
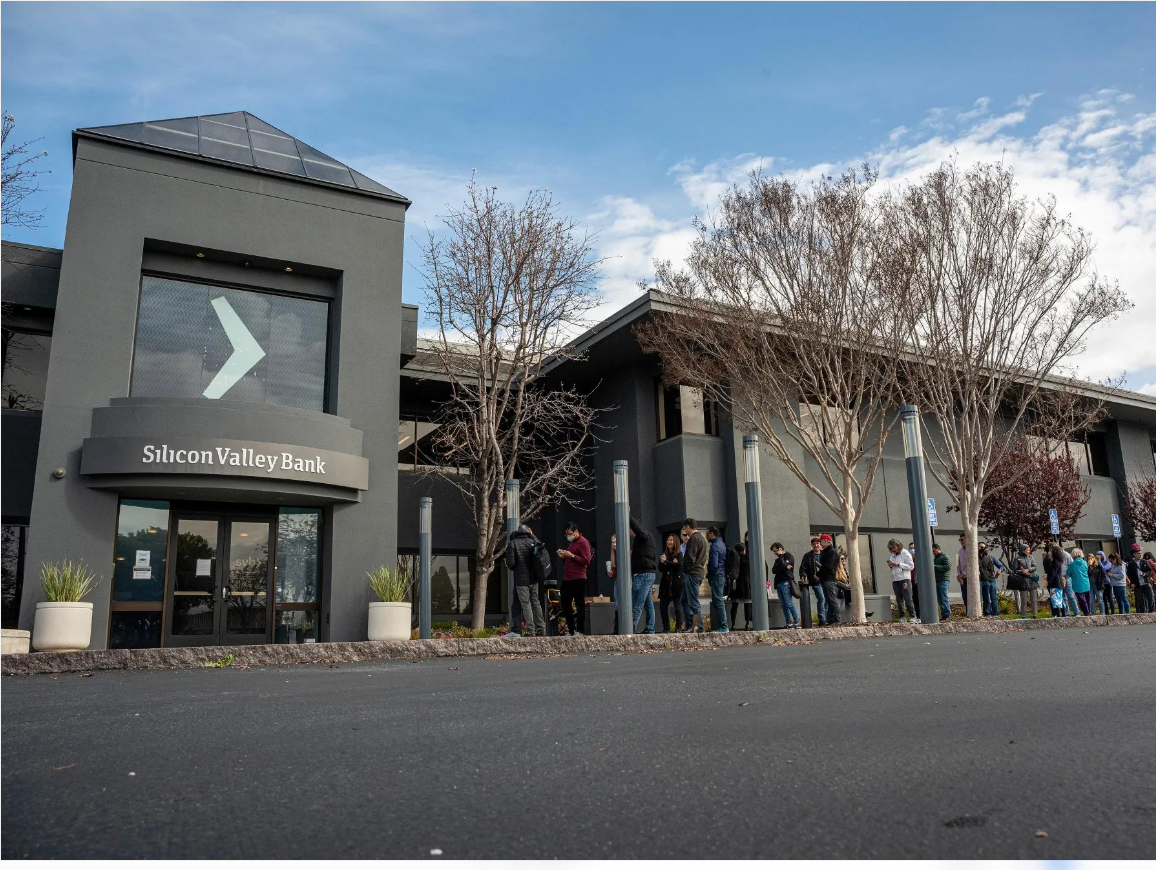
When concerns about its financial position intensified, depositors attempted to remove funds on a scale the bank could not withstand.
Regulators closed Silicon Valley Bank in March 2023.
The failure demonstrated how interest-rate risk, concentrated deposits and declining customer confidence can combine to create a banking crisis.
Why Investors Questioned the Bank’s Auditors
External auditors play an important role in financial markets.
Their responsibility is to examine financial statements and provide an independent opinion on whether those statements are presented fairly under the applicable accounting framework.
Investors use audited financial statements when evaluating a company’s profitability, financial condition and exposure to risk.
However, an audit does not guarantee that a company will remain financially stable or that every business risk has been eliminated.
Auditors assess financial reporting under defined professional standards. They do not replace bank management, prudential regulators or investors in evaluating every potential business risk.
The litigation following Silicon Valley Bank’s collapse raised questions about financial reporting and the information available to investors before the bank failed.
KPMG’s settlement resolves its part of the dispute without an admission of wrongdoing.
The case nevertheless illustrates why audit quality and investor confidence are closely connected.
When a major financial institution collapses, shareholders often examine whether its financial disclosures adequately communicated material risks.
Norway’s Sovereign Wealth Fund Played a Significant Role
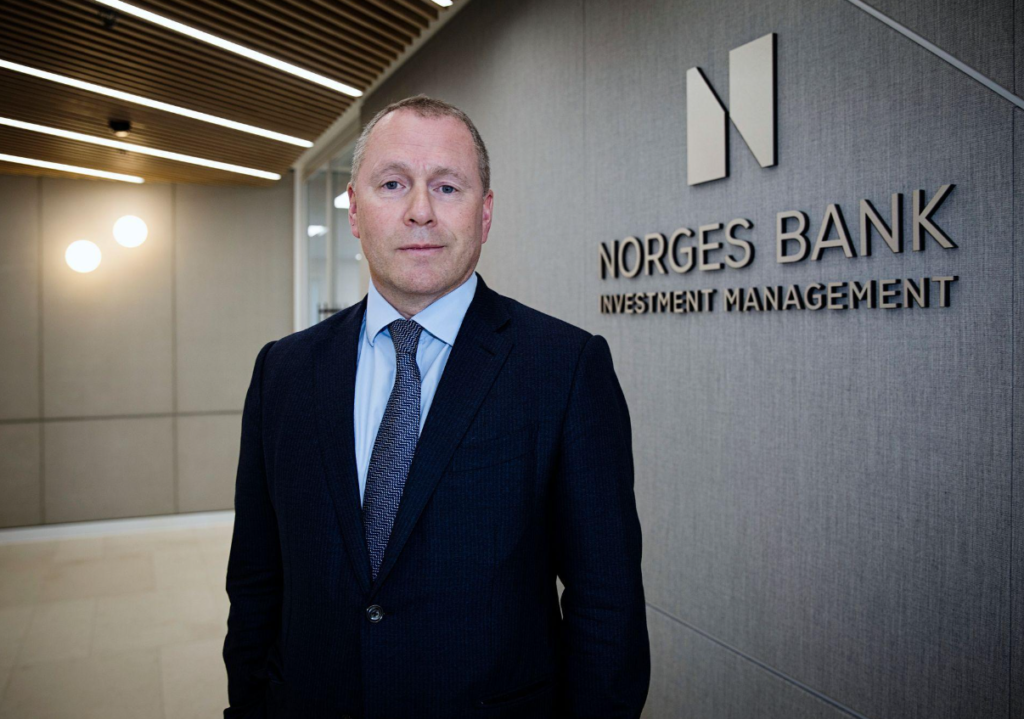
Norway’s sovereign wealth fund was among the investors affected by Silicon Valley Bank’s failure.
The fund manages investment assets built from Norway’s petroleum revenues and is one of the world’s largest institutional investors.
According to Reuters, it held approximately 1% of Silicon Valley Bank at the end of 2022, with that investment valued at US$137.9 million.
The fund has significant holdings across global equity markets, making corporate governance and financial reporting important considerations in its investment activities.
Following the settlement announcement, the fund emphasized the importance of recovering investor losses and maintaining confidence in public markets.
Its involvement demonstrates how the collapse of a single financial institution can affect investors far beyond the country where that institution operates.
International pension funds, sovereign wealth funds and asset managers frequently invest in banks and other financial companies.
When those investments suffer major losses, the financial consequences can spread across a wide network of institutional shareholders.
What the Settlement Means for KPMG
KPMG is one of the world’s largest professional services networks, providing auditing, tax and advisory services.
Its role in auditing financial institutions places it within an industry where public confidence is particularly important.
Banks operate with substantial financial leverage and depend heavily on the confidence of depositors, investors and regulators.
Audited financial statements form part of the information used to evaluate their financial condition.
In responding to the settlement, KPMG said it continued to stand behind its audits of Silicon Valley Bank.
The firm described the agreement as a strategic decision to move forward rather than an acknowledgment of wrongdoing.
The financial settlement therefore should not be interpreted as a judicial finding that KPMG violated auditing standards.
Nevertheless, major litigation involving auditors can draw attention to how accounting firms assess complex financial institutions and communicate financial-reporting risks.
The Broader Problem of Banking Risk Management
Silicon Valley Bank’s collapse exposed weaknesses that extend beyond financial reporting.
One of the central problems was the relationship between the bank’s assets and liabilities.
Banks accept deposits and use funds to support lending, securities investments and other financial activities.
However, deposits may be withdrawn much more quickly than long-term investments can be converted into cash without losses.
This creates liquidity risk.
When interest rates rise, banks holding long-duration fixed-income securities may also experience declines in the market value of those investments.
That creates interest-rate risk.
These risks become especially dangerous when a bank has a concentrated depositor base.
Silicon Valley Bank’s customer relationships were heavily concentrated among technology companies and venture-backed businesses, many of which faced similar financial pressures.
As confidence weakened, deposit withdrawals accelerated.
The episode demonstrated that a bank can encounter severe financial difficulties even when many of its assets are traditionally considered relatively safe.
What Other Banks Can Learn From the Collapse
The failure of Silicon Valley Bank provides several lessons for financial institutions.
First, banks must assess how changes in interest rates affect the value and liquidity of their assets.
Second, they must understand the behaviour of their depositors, particularly when customers have large balances that can be withdrawn quickly.
Third, financial institutions need effective systems for identifying risks that may appear manageable individually but become dangerous when combined.
Finally, communication matters.
Investors and depositors need reliable information about financial conditions, while management must respond quickly when confidence begins to deteriorate.
The collapse also highlights the importance of independent oversight.
Boards, auditors and regulators have different responsibilities, but each contributes to the wider system intended to protect financial stability.
Why the Settlement Matters for Global Banking
The KPMG agreement is more than a legal development involving a failed American bank.
It reflects the continuing consequences of a banking crisis that raised questions about financial supervision and investor protection.
Major financial institutions operate within interconnected markets where confidence can change rapidly.
When a bank fails, the effects may reach depositors, shareholders, other banks and international investors.
The settlement also illustrates the financial consequences that can follow disputes over corporate disclosures and external auditing.
However, monetary compensation cannot fully reverse the wider economic disruption caused by a banking failure.
The more important long-term question is whether the lessons from Silicon Valley Bank lead to stronger risk management, clearer financial reporting and more effective oversight.
THE ABE TAKE
The Silicon Valley Bank KPMG settlement illustrates a fundamental principle of banking: confidence is one of the financial system’s most valuable assets.
Silicon Valley Bank’s collapse was not simply the result of falling bond prices. It reflected a combination of concentrated deposits, exposure to changing interest rates and a rapid loss of customer confidence.
The US$224.5 million settlement represents a significant step in the legal process, but it does not establish wrongdoing by KPMG or resolve the entire investor lawsuit.
For banks, the lesson is that financial stability requires more than profitable operations. Institutions must understand their risks and prepare for conditions that differ substantially from their expectations.
For auditors, the case reinforces the importance of credible financial reporting and public trust, while also highlighting the distinction between auditing financial statements and guaranteeing a bank’s future performance.
For investors, it demonstrates why understanding a financial institution’s funding structure, asset exposure and governance is essential.
A bank’s reputation may take decades to build, but a loss of confidence can threaten its survival in a matter of days.
The continuing legal consequences of Silicon Valley Bank’s collapse show that the financial impact of a banking failure can persist long after the institution itself has disappeared.
ABE MAGAZINE
Understand More. Think Bigger.