ABE FOUNDERS | SEPTEMBER 26, 2026
Africa’s technology story is often told through the same handful of cities.
Lagos. Nairobi. Cairo. Cape Town.
They have become the continent’s most visible startup hubs, attracting founders, venture capital firms and international attention. But some of Africa’s most interesting companies are being built outside those established centres — in markets where raising capital, finding experienced technology talent and convincing investors to pay attention can be considerably harder.
Cameroon is one of them.
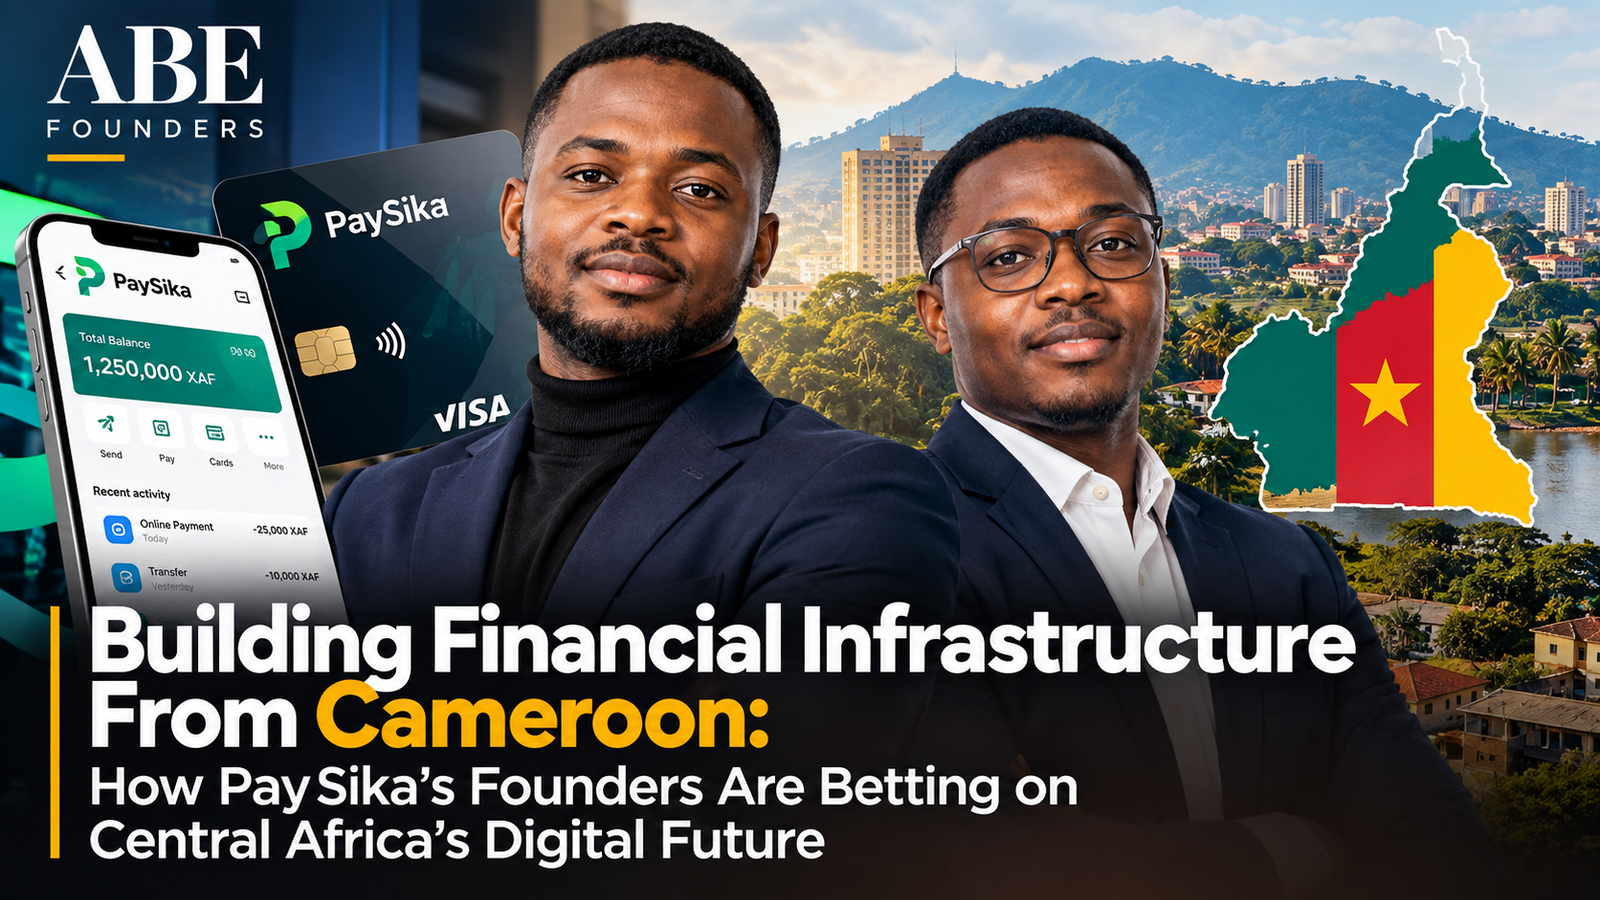
And from there, entrepreneurs Roger Nengwe Ntafam and Stezen Bisselou-Nzengue are building PaySika, a financial technology company attempting to make digital financial services and international payments more accessible across Central Africa.
That mission has now attracted new institutional backing.
On September 15, African pre-seed investment program Madica announced PaySika among five new portfolio companies, marking Madica’s first investment in Cameroon. Each company is eligible for up to $200,000 in investment, alongside an 18-month program providing mentorship, executive coaching and access to investors.
For PaySika, the investment represents more than another funding announcement.
It is a bet on whether a financial technology company built for one of Africa’s less-funded startup markets can eventually build financial infrastructure serving a much larger region.
THE PROBLEM PAYSIKA IS TRYING TO SOLVE
For many consumers in developed economies, paying for an international subscription, shopping online or obtaining a payment card can feel routine.
The experience can be considerably different in parts of Central and Francophone Africa.
PaySika is attempting to close that gap by providing digital financial services through smartphones rather than relying on traditional bank branches.
The company offers virtual and physical payment cards and account-management tools that allow customers to make local and international transactions. Madica describes PaySika as a digital neobank serving consumers and small and medium-sized businesses across Central Africa.
PaySika’s current website promotes both virtual and physical debit cards, alongside features allowing customers to manage cards, establish limits and make payments internationally.
But the larger ambition extends beyond issuing cards.
PaySika wants to create a bridge between the financial systems people already use locally and the increasingly global digital economy.
That matters in a world where participation in business is becoming increasingly international. A freelancer may need to receive money from another country. A small company may need to purchase software from an overseas provider. A creator may receive income from an international platform. A consumer may want to purchase a product from a foreign merchant.
Access to international payment infrastructure can therefore influence much more than convenience.
It can influence who gets to participate in the digital economy.
TWO FOUNDERS, ONE REGIONAL AMBITION
PaySika was founded by Roger Nengwe Ntafam and Stezen Bisselou-Nzengue.
From the beginning, their ambitions stretched beyond Cameroon.
When PaySika announced in 2023 that it had joined Visa’s Fintech Fast Track program, the company described itself as developing digital banking solutions for French-speaking African markets, beginning with Cameroon and seeking expansion across Central Africa.
The Visa program provided PaySika access to Visa’s payment network expertise and ecosystem as the startup worked on expanding its payment services.
At the time, Nengwe framed the company’s mission around making financial services easier to access and manage digitally.
Three years later, the regional ambition remains.
Following Madica’s investment, Nengwe said PaySika is building financial infrastructure designed to make banking services more accessible and practical for consumers and businesses across Central Africa.
That distinction is important.
PaySika is not simply trying to build another consumer app.
It is attempting to solve a financial infrastructure problem.
HOW PAYSIKA ACTUALLY OPERATES IN CAMEROON
Fintech companies can sometimes appear to consumers as digital banks even when the regulatory structure behind them is more complicated.
PaySika provides an important example.
According to the company’s current terms, PaySika Cameroon SAS operates as a distributor agent of Ecobank Cameroon, a regulated credit institution and Visa member authorized to issue cards in Cameroon.
The arrangement gives PaySika a way to build the customer-facing technology and payment experience while operating within existing banking and payment infrastructure.
Its cards can be used for purchases and withdrawals through the Visa network, subject to applicable regulations and available balances.
This partnership model illustrates something broader about fintech.
The companies consumers interact with do not necessarily need to replace traditional banks entirely.
Sometimes their opportunity is to build a better technological layer on top of regulated financial infrastructure.
That can mean simpler onboarding, better interfaces, easier card management and financial products designed around customers whose needs have historically received less attention.
WHY CAMEROON MAKES THIS STORY DIFFERENT
The geography may be as important as the product.
African venture capital has historically been concentrated heavily in a few major ecosystems, particularly Nigeria, Kenya, South Africa and Egypt.
Markets outside those centres can have strong entrepreneurs and large problems to solve while attracting significantly less institutional investment.
Madica was created partly to address that imbalance.
Its latest investments expanded the program into Cameroon and Algeria for the first time, while its portfolio now reaches multiple African markets.
PaySika therefore represents two bets simultaneously.
The first is a bet on fintech.
The second is a bet on geography.
Can venture-scale technology companies emerge from African markets that international investors have historically overlooked?
Madica believes they can.
The firm’s head, Emmanuel Adegboye, said its strategy is based on the belief that strong founders can emerge throughout Africa even though early-stage capital remains concentrated in relatively few ecosystems.
PaySika now gets an opportunity to test that thesis.
THE CENTRAL AFRICAN OPPORTUNITY
Cameroon itself is only part of the potential market.
PaySika’s broader target is Central Africa, including the CEMAC economic region, where multiple countries share regional institutions and the Central African CFA franc.
That creates an intriguing possibility.
A company capable of building useful financial infrastructure in Cameroon may eventually be able to adapt that technology for neighbouring markets facing similar payment and financial-access problems.
But regional expansion in financial services is not automatic.
Each market brings regulation, licensing requirements, compliance obligations, consumer behaviour, banking relationships and competition.
A product working in Cameroon cannot simply be copied across borders without considering those differences.
That makes execution particularly important.
PaySika has demonstrated that it can build a product and establish institutional partnerships. The much larger question is whether it can turn that foundation into a scalable regional financial business.
THE $200,000 QUESTION
Madica’s investment should also be viewed in perspective.
PaySika has not suddenly become a heavily funded African fintech.
Madica says portfolio companies can receive up to $200,000, while also receiving 18 months of structured operational support.
At the pre-seed stage, however, the significance of capital is not necessarily its absolute size.
It is what founders can prove with it.
Can PaySika acquire customers efficiently?
Can it deepen usage rather than merely accumulate registrations?
Can it establish additional financial partnerships?
Can it expand geographically without allowing compliance and operating costs to overwhelm the business?
Can it eventually attract the larger rounds of capital required to compete in financial technology?
Those milestones will matter far more than the headline attached to one investment.
Madica itself generally targets companies that already have an MVP, ideally some paying customers, have raised little institutional capital and are operating in Africa with full-time local founders.
That makes this stage particularly revealing.
The company now has to convert early validation into a business capable of scaling.
AFRICA’S NEXT STARTUP HUBS MAY NOT LOOK LIKE THE LAST ONES
There is a broader lesson in PaySika’s story.
Successful technology ecosystems tend to create reinforcing cycles.
A startup succeeds. Employees gain experience. Some become founders. Investors become more comfortable with the market. International capital arrives. More companies are created.
Eventually a city develops an ecosystem rather than merely producing isolated startups.
Nigeria, Kenya, Egypt and South Africa have benefited from versions of that cycle.
The next stage of African technology could involve that network spreading further.
Cameroon will not become a major venture ecosystem because one investor wrote one cheque.
But institutional investors making their first investments in markets such as Cameroon matters because somebody has to make the first bet.
If companies such as PaySika succeed, they can make the next founder easier to fund.
And the founder after that easier still.
🔴 THE ABE NEWS TAKE
The most interesting thing about PaySika is not the size of its latest investment.
It is where the company is being built and what its founders are trying to connect.
For decades, access to global financial infrastructure has been uneven. The internet made it possible for a young entrepreneur in Douala to reach customers thousands of kilometres away, but the financial infrastructure required to participate fully in that economy has not always evolved at the same speed.
That gap creates an opportunity.
Nengwe and Bisselou-Nzengue are betting that Central Africa does not simply need more banks. It needs financial technology designed around how a new generation actually earns, spends and moves money.
Whether PaySika ultimately becomes a major regional financial company remains an open question. Its latest backing is an early-stage investment, not proof that the business model has already won.
But that is precisely why the company belongs in ABE Founders.
The purpose is not only to document entrepreneurs after they become famous.
It is to watch serious builders while they are still building.
And sometimes the companies that eventually change an industry begin far away from the places everyone else is watching.
ABE NEWS
Business. Money. Style. The News.
Understand More. Think Bigger.