ABE MAGAZINE | FINANCE & BANKING
October 13, 2026
America’s largest banks have reported billions of dollars in quarterly profits, supported by consumer spending, lending and financial-market activity. Yet their results also reveal growing tensions beneath the economy’s apparent strength, from volatile bond markets to persistent inflation and increasingly expensive borrowing.
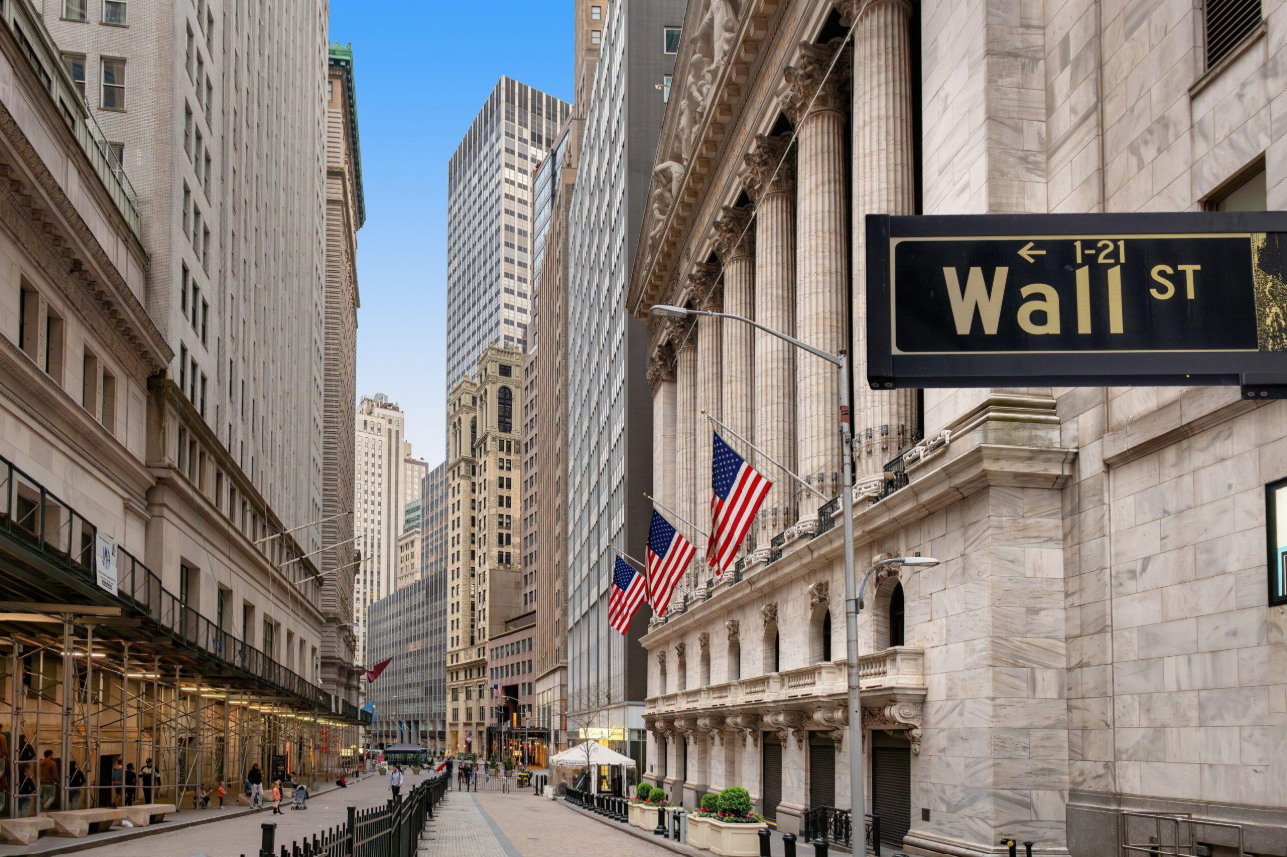
Wall Street Delivers Profits in an Uncertain Economy
America’s largest financial institutions entered the latest earnings season facing a difficult question: could their profitability withstand rising interest rates, geopolitical uncertainty and renewed volatility across global markets? The first major results, released on October 13, suggest that the banking industry remains financially strong, although its performance is becoming increasingly uneven. JPMorgan Chase, Goldman Sachs, Citigroup and Wells Fargo all reported substantial third-quarter profits, offering an important indication that consumer spending and corporate activity have continued despite mounting economic pressures.
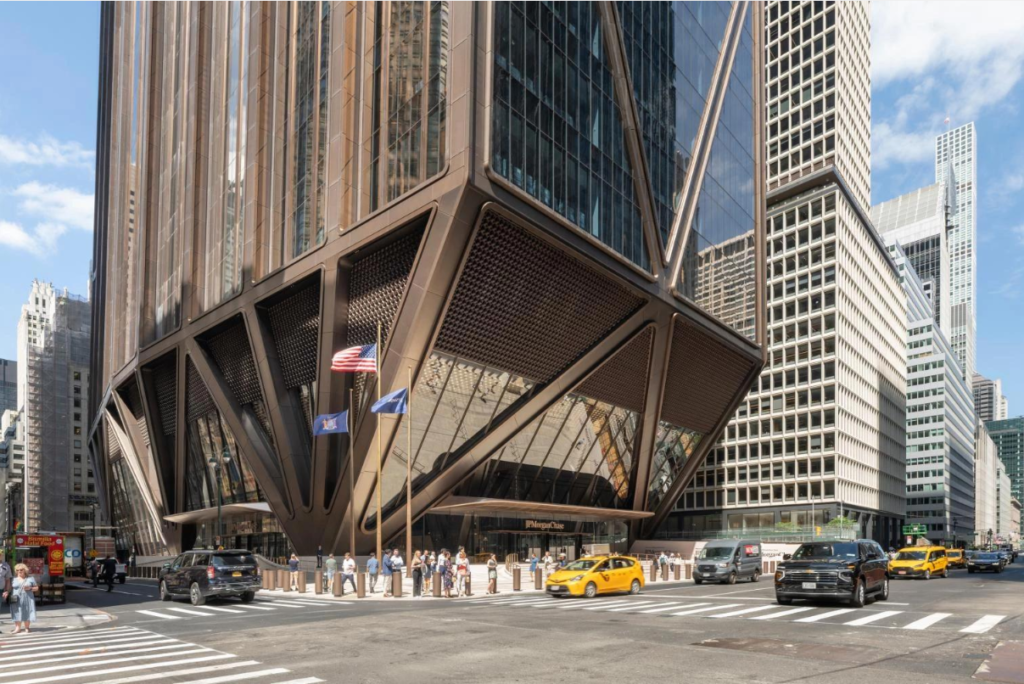
JPMorgan Chase reported net income of $15.3 billion and revenue of approximately $50.2 billion for the quarter. Goldman Sachs generated $5.29 billion in earnings on $18.68 billion in revenue, marking one of its strongest revenue performances. Citigroup reported approximately $5.2 billion in profit, while Wells Fargo earned $5.95 billion. Taken together, the results demonstrate the extraordinary earnings capacity of America’s largest banks, whose operations extend across consumer lending, corporate finance, securities trading and international financial services.
Nevertheless, the headline figures conceal important differences. Goldman Sachs benefited from particularly strong equities trading, while JPMorgan experienced slower investment-banking activity and losses associated with investment securities. Wells Fargo’s profit increased, but its revenue fell short of market expectations. The contrasting results suggest that banks are not benefiting equally from the economic environment, even when their overall profits remain substantial.
The Economy Is Stronger Than Many Expected
One reason banks continue to generate large profits is that American consumers and businesses have remained active. Consumer spending supports payment processing, credit-card activity and demand for financial services, while business investment creates opportunities for commercial lending, financing and advisory work. These activities provide banks with multiple sources of revenue, allowing stronger performance in one division to offset weakness elsewhere.
JPMorgan chief executive Jamie Dimon pointed to continued business investment and consumer spending as important sources of economic strength. His assessment reflects a broader reality: despite persistent concerns about inflation and interest rates, the United States has not experienced the widespread collapse in private-sector activity that some earlier forecasts anticipated. Large companies continue to invest, households continue to spend and financial institutions remain central to the movement of capital throughout the economy.
Yet resilience does not necessarily mean that financial conditions are comfortable. Consumers may maintain spending while relying more heavily on credit, and businesses may continue investing despite facing higher financing costs. For banks, the crucial question is whether customers can sustain their financial commitments if economic conditions deteriorate. Strong current profits offer reassurance, but they do not eliminate the need to monitor repayment performance and future borrowing demand.
Trading Profits Reveal a Divided Financial Market
The performance of investment banks provides another revealing perspective on the economy. Financial-market volatility can create profitable opportunities for trading businesses, particularly when investors rapidly adjust their positions in response to changing interest-rate expectations, geopolitical events or corporate developments. However, uncertainty can also discourage companies from issuing securities, pursuing acquisitions or undertaking other transactions that generate investment-banking fees.
Goldman Sachs illustrates this contrast. The bank’s quarterly revenue increased significantly, supported by a powerful performance in equities trading. Its results demonstrate how a sophisticated trading operation can benefit from active financial markets even when the broader economic environment remains unsettled. At the same time, weaker conditions in parts of the bond market show that trading performance is far from uniform.
JPMorgan faced its own challenges, including slower investment-banking activity and a $658 million loss associated with investment securities. These developments reflect the consequences of changing market conditions for institutions that hold substantial financial assets. When interest rates and bond yields move sharply, the value of existing securities can change, creating gains or losses that complicate an otherwise profitable quarter.
The distinction matters because strong trading profits should not automatically be interpreted as evidence of a healthy financial market. Banks can earn substantial revenue while their customers confront uncertainty, financing difficulties and rapidly changing asset prices. Understanding the economy therefore requires examining not only how much financial institutions earn, but also where those earnings originate.
Higher Interest Rates Create Winners and Losers
Interest rates remain one of the most consequential forces affecting the banking industry. Banks generally earn income from lending money and investing in interest-bearing assets, while paying interest to depositors and other funding providers. The difference between these revenues and funding costs helps determine profitability, although the relationship becomes more complicated when rates move sharply.
Wells Fargo’s latest results demonstrate how lending activity and interest income can support earnings. The bank reported a roughly 6% increase in quarterly profit, helped by loan growth and higher interest income. However, rising rates can also make borrowing more expensive for households and companies, potentially discouraging new loans or increasing repayment difficulties over time.
The effects extend well beyond banking balance sheets. Higher mortgage rates can reduce housing affordability, while more expensive business loans can discourage expansion and investment. Governments also face greater costs when refinancing debt. For financial institutions, a period of elevated rates may support certain revenue streams while simultaneously weakening demand and increasing credit risks.
This tension helps explain why investors are examining bank results so closely. The immediate profitability of lending does not necessarily indicate whether those loans will remain attractive or manageable throughout their duration. A strong banking system must generate earnings while maintaining sufficient capital and liquidity to withstand changing economic conditions.
What the Results Mean for Investors and Businesses
For investors, the latest earnings offer a mixed picture. Large banks remain capable of producing substantial profits, but financial markets are increasingly sensitive to inflation, bond yields and geopolitical developments. Bank shares had underperformed the broader American stock market in the months preceding these results, suggesting that investors were already concerned about the sustainability of future earnings.
For businesses, the implications are equally important. Banks influence the availability and cost of capital, affecting everything from commercial property development to corporate acquisitions and small-business expansion. If financing becomes more expensive or lenders become more cautious, otherwise profitable companies may postpone investments. Conversely, a well-capitalized banking system can continue supporting economic activity even during periods of uncertainty.
The results also underline the importance of distinguishing between financial-sector profitability and wider economic prosperity. A bank can report record trading revenue while smaller businesses struggle with borrowing costs. Consumers can continue spending while becoming more financially stretched. Strong earnings are valuable evidence of institutional resilience, but they provide only one perspective on the health of the economy.
THE ABE TAKE
Wall Street’s latest earnings demonstrate that America’s largest banks remain exceptionally profitable, but profitability alone is an incomplete measure of financial stability. The more important question is whether those earnings are being generated within an economy that can sustain expensive borrowing, volatile markets and persistent inflation without creating deeper vulnerabilities.
The contrasting performances of JPMorgan, Goldman Sachs, Citigroup and Wells Fargo reveal how differently financial institutions can experience the same economic conditions. Some benefit from active trading, others from lending, and still others from the continuing demand for financial services. That diversity strengthens the banking system, but it also makes headline profit figures a potentially misleading guide to the broader economy.
For policymakers, investors and business leaders, the lesson is straightforward: strong banks are an important foundation for economic resilience, but they cannot guarantee it. The real test will come if today’s financial pressures begin to weaken the consumers and businesses on which their profitability ultimately depends.
ABE MAGAZINE
Understand More. Think Bigger.